
Blogs
PW Consulting: Global Moving Table Grinding Machine Market Hits $3.15B in 2025, 4.62% CAGR to 2032
By pmarketresearch, 2026-09-16
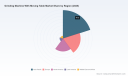
Strategic Outlook on the Worldwide Grinding Machine With Moving Table Market: Navigating 2026 and Beyond
The global manufacturing landscape is undergoing a quiet convergence of precision demands, automation mandates, and capital efficiency pressures. Within this shifting terrain, the worldwide market for grinding machines with moving tables stands as a critical enabler of high-tolerance component production. Our newly published research tracks this segment from 2020 through a ten-year forecast window ending in 2032, offering a granular, decision-ready map for executives navigating procurement, capacity planning, regional expansion, and technology investment. Grounded in 2025 as the base year, the analysis captures a mature but structurally evolving market, where incremental growth compounds into meaningful strategic advantage when paired with disciplined market intelligence.
A Decade of Measured Expansion: Market Trajectory and Structural Signals
The market has demonstrated a consistent upward trajectory across the historical review period, reflecting the steady replacement cycle of precision machining capacity and the incremental adoption of moving-table configurations that enable multi-axis handling, reduced setup changeover, and improved surface integrity. By the close of the forecast horizon, the market is projected to surpass the four-billion threshold in USD millions, a milestone that underscores both the durability of core industrial demand and the compounding effect of modernization investments. The compound annual growth rate of approximately 4.62 percent frames a market that is expanding at a pace faster than population-driven consumption but slower than speculative technology cycles, making it a textbook case of structurally supported, capex-sensitive growth.
This trajectory is not uniform in its drivers. The historical years reveal how production backlogs, supply chain recalibrations, and regional manufacturing rebalancing shaped purchasing behavior. In the forward window, the growth path is increasingly influenced by equipment lifecycle economics, labor availability, and the accelerating digitization of shop floors. Our forecast model integrates these variables to illustrate how revenue concentration, replacement demand, and technology upgrades will interact over the depreciation cycles of installed base assets. For strategic planners, the key takeaway is that growth in the period ahead will be earned through timing, configuration selection, and the ability to align machine capabilities with rising tolerances and unattended-operation expectations.
Report Architecture: Operational Intelligence for Decision Makers
The study is constructed to translate market behavior into procurement and investment decisions. It maps the competitive terrain, tracks structural shifts, and isolates the variables that determine return on equipment investment. Below is a structured overview of the analysis framework:
- Core market sizing and multi-year forecasting anchored to a 2025 baseline, with explicit linkage to replacement cycles and capacity utilization patterns
- Technology configuration evaluation that distinguishes moving-table architectures from alternative grinding setups, including throughput implications and precision pathway comparisons
- Competitive profiling of leading OEMs and their strategic positioning, product differentiation, and regional presence
- Macro and micro demand drivers, including raw material cost exposure, sustainability mandates, and Industry 4.0 adoption curves
- Strategic implications for capacity planning, after-sales service design, and distributor/manufacturer collaboration models
Each section is designed to feed directly into capital allocation discussions, RFP design, and regional entry or partnership evaluation. Rather than stopping at descriptive trends, the report isolates the decision points that determine which investments outperform over a seven-year horizon.
Gear Grinding Machine Market
Who Moves the Table: Competitive Landscape and Strategic Profiles
The competitive set in this market is defined by a blend of European precision heritage, Asian scale and speed-to-market, and regional specialists capable of serving heavy-industry and niche tolerance requirements. Market concentration data indicates that the top three players account for a meaningful but not dominant share, while the top five approach a near-majority position, signaling a landscape with strong incumbents and continuing room for targeted differentiation. This structure matters: it implies pricing discipline in mainstream configurations, yet significant latitude for technology-led differentiation in heavy-duty, high-precision, and hybrid-operation segments.
Danobat has built a notable profile around hybrid operations that combine grinding with hard turning, milling, boring, and drilling in a single setup, supported by hydrostatic bearings and sub-micron precision on large workspace envelopes. This configuration philosophy reduces part handling and accelerates complex component throughput, an increasingly valuable attribute as manufacturers seek to compress process steps. In early 2026, a precision gear manufacturer expanded its capabilities by adding a Danobat universal OD configuration, illustrating how moving-table platforms are being adopted as enabling nodes in specialized production cells.
Worldwide Grinding Machine With Moving Table Market
Herkules continues to anchor its positioning around roll grinding with traveling table and traversing saddle designs, emphasizing large-roll handling, automatic loading and unloading, and steady-rest integration. For segments where workpiece size and rotational stability define capability requirements, this architectural focus translates into durable competitive advantage. Meanwhile, the Robbi Group provides universal CNC/PLC cylindrical platforms with hydrodynamic spindles and robot integration pathways, aligning with the broader move toward flexible, programmable cells. Morara’s MH series extends this logic to external and internal cylindrical work, including heavy-duty applications such as railway axles, while HMT Machine Tools contributes horizontal spindle reciprocating table CNC surface grinding platforms designed for rigid, programmable axis control in flat and profile applications.
JTEKT Machinery brings high-production precision with configurations compatible with moving-table principles, supporting throughput-sensitive environments. In Italy, Gioria, AZ, and Grinding Technology’s Morara presence reinforce a regional strength in conventional and CNC table-moving cylindrical designs, including hydraulic and controlled variants with high payload capacities. Across southern Europe, these players demonstrate how configuration specialization and application-specific tuning create defensible niches. LGB Scop supplies surface grinding platforms with moving table configurations for industrial use, while Dowell Machine contributes rotary table surface grinders built on high-quality castings, offering vertical spindle variants adaptable to precision requirements. Kehren focuses on high-precision surface grinding with rotary tables and vertical/horizontal spindle orientation, emphasizing creep feed and profile grinding systems. UNITED GRINDING, through its MÄGERLE lineage, offers large-diameter rotary table centers with substantial load capacity, addressing heavy turbine and coupling components with hydrostatically mounted tables.
Strategically, the field is less about a single dominant playbook and more about configuration-to-application fit, service ecosystem depth, and the ability to reduce integration friction for end users. Our report profiles these players not simply to list strengths, but to surface where each is most likely to win, where substitution risk is highest, and how procurement teams can use competitive spacing to negotiate capability and service terms.
Forces Shaping the Next Cycle: Dynamics, Materials, and Manufacturing Mandates
The market’s forward movement is being shaped by overlapping forces that influence both demand timing and equipment economics. Industry 4.0 integration is steadily shifting grinding platforms from isolated workstations toward connected assets with predictive maintenance capability, optimized cycle control, and improved resource efficiency. In parallel, energy efficiency mandates and sustainability initiatives are nudging manufacturers toward designs with lower power consumption and more effective cooling architectures. On the shop floor, automation and smart factory trends, including digital twins and connected CNC systems, are accelerating fleet modernization for unattended operation and higher repeatability.
These dynamics intersect with material cost realities. Iron prices in early 2026 reached levels that directly affect the cost base of cast iron and steel structures used in machine beds and tables, while global scrap price movements across regions have influenced recycled steel supply for machine frames. For capital equipment buyers, this translates into a more variable cost environment where lead-time planning, specification choices, and service-part inventories must be managed with greater foresight. The research integrates these inputs to help manufacturers evaluate total cost of ownership rather than sticker price alone, especially when comparing moving-table configurations with alternative architectures.
Beyond cost, regulation and labor dynamics are altering the value proposition of moving-table designs. Where skilled labor availability is constrained, the appeal of configurations that reduce setup complexity and enable programmed handling increases. Where tolerance requirements tighten in aerospace, defense, medical device, and automotive applications, the precision pathway offered by stable table mechanics and controlled wheel movement becomes a competitive differentiator. The report synthesizes these signals into a demand-side narrative that explains where growth will concentrate and which buyers are most likely to accelerate replacement or expansion spending.
Where Precision Meets Volume: Application Realities and Demand Concentration
The demand base spans multiple industrial ecosystems, each with distinct tolerance requirements, batch profiles, and capital cycles. General machinery and automotive sectors represent substantial portions of end-user demand, driven by high-volume component production and recurring replacement of worn or precision-degraded surfaces. Aerospace and defense applications contribute a structurally important layer, where tighter tolerances, material complexity, and longer procurement cycles elevate the strategic value of capable grinding platforms. Medical device manufacturing, though smaller in relative scale, reflects a demand segment that prioritizes surface integrity, repeatability, and contamination-controlled processes.
These application profiles matter because they shape not only which machines are purchased, but how they are specified, serviced, and integrated into production cells. A moving table can change changeover times, part orientation flexibility, and wheel-to-workpiece engagement consistency. Our analysis examines these operational consequences without reducing them to oversimplified generalizations, allowing procurement and engineering leaders to map application requirements to configuration strengths with greater precision.
Regionally, demand is distributed across established industrial centers and emerging capacity hubs, with Asia Pacific representing the largest share of market activity, followed by Europe and North America. This distribution reflects the interplay of installed base age, local manufacturing intensity, and the pace of modernization. Because regional dynamics are heavily influenced by local labor conditions, energy costs, and supply chain structure, a single global growth figure is insufficient for operational planning. The study provides the regional context needed to interpret where investment timing is favorable, where service coverage matters most, and where local partnerships can reduce integration risk.
Translating Forecast Into Action: Strategic Implications for 2026 and Beyond
For executives planning the 2026 decision cycle, the most valuable use of this research is not simply to confirm that growth will continue, but to determine how to position for it. The forecast period to 2032 reveals a market that rewards discipline in three areas: timing, configuration selection, and ecosystem readiness.
- Timing: Replacement cycles interact with macroeconomic signals, raw material volatility, and technology adoption curves. Companies that align procurement with credible capex windows can reduce cost exposure and capture capability upgrades at optimal points in the cycle.
- Configuration selection: Moving-table architectures are not universally superior, but they offer distinct advantages in applications requiring reduced handling, improved surface consistency, and programmable axis control. Matching configuration to application profile is central to achieving the intended return on equipment investment.
- Ecosystem readiness: Automation, Industry 4.0 integration, and service coverage increasingly determine real-world performance. Buyers benefit from evaluating not only the machine but the software interfaces, maintenance model, and training path that determine uptime and repeatability.
These implications extend beyond purchasing. For manufacturers, the study informs product roadmap priorities, where hybrid capability, heavy-duty payload capacity, and energy-efficient design are most valued. For distributors and service providers, it identifies where coverage gaps create competitive openings and where regional density strengthens account retention. For investors and strategists, it clarifies where concentration remains limited and where application-specific differentiation can sustain margin resilience.
Why This Study Matters Now: The Case for Actionable Intelligence
A market growing at a steady but not spectacular pace can still generate disproportionate strategic outcomes for organizations that understand its internal structure. The difference between reacting to demand and shaping it lies in the quality of intelligence available at the point of decision. Our Worldwide Grinding Machine With Moving Table Market report is built to provide that intelligence: a forecast framework, competitive mapping, application context, and dynamic drivers that together support capital planning, vendor evaluation, and regional strategy.
To access the complete segmentation detail, regional breakdowns, competitive positioning tables, and forward modeling, request the full study through our official research portal. The source page contains the full intelligence set required to translate these strategic themes into procurement specifications, investment memos, and market-entry evaluations. In a market where configuration fit, service depth, and timing determine outcomes, complete data is not a luxury; it is the foundation of durable advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Grinding Machine With Moving Table Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: JAK Inhibitors Market to Reach $40.5B by 2032, 14.01% CAGR
By pmarketresearch, 2026-09-16
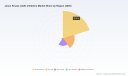
Navigating the Next Wave: Strategic Insights from the 2026 Worldwide JAK Inhibitors Market Intelligence
The Janus Kinase (JAK) inhibitor landscape is undergoing a fundamental transformation. As the therapeutic class matures beyond its initial breakthrough era, pharmaceutical executives, investors, and healthcare strategists face a complex matrix of clinical differentiation, regulatory reinterpretations, patent cliff disruptions, and shifting reimbursement architectures. Our newly released Worldwide JAK Inhibitors Market research delivers the analytical rigor required to navigate this inflection point. This publication is not merely a retrospective summary of historical sales; it is a forward-looking decision architecture designed explicitly for enterprise strategy in 2026 and beyond. By mapping the trajectory from baseline market conditions through the 2026-2032 forecast horizon, the study provides a structured lens through which stakeholders can anticipate competitive displacement, evaluate pipeline positioning, and allocate capital with precision.
The Macro Trajectory: Why 2026 Serves as a Strategic Inflection Point
Historical momentum establishes the foundation. Between 2020 and 2025, the global JAK inhibitors market expanded from approximately 7.4 billion to 16.2 billion USD, reflecting a sustained adoption curve across inflammatory, autoimmune, and hematologic indications. The forecast period extends this trajectory through 2032, with base-year positioning in 2025 and a compound annual growth rate of 14.01 percent. By mid-decade, the market is projected to cross the 17.7 billion threshold, with continued acceleration pushing toward the 40 billion mark by the close of the forecast window. These figures represent more than aggregate revenue; they signal a structural reallocation of therapeutic preference, payer budget prioritization, and clinical guideline integration.
For corporate strategy teams, the 2026 baseline is particularly consequential. It sits at the intersection of multiple simultaneous forces: the expiration of foundational patents, the widening of label expansions into pediatric and niche dermatology populations, the maturation of next-generation selective molecules, and the ongoing recalibration of safety monitoring frameworks. The 14 percent CAGR does not emerge in a vacuum. It is the product of overlapping demand drivers, supply chain adaptations, and commercialization agility. Understanding how these variables compound—and where they diverge across therapeutic categories and geographic commercial footprints—requires the granular segmentation and scenario modeling contained in the full report.
Structural Pillars of the Analysis: What the Report Delivers
The research is engineered to translate macroeconomic signals into actionable commercial intelligence. Rather than presenting static snapshots, the study employs a multi-dimensional segmentation architecture that enables clients to isolate the levers most relevant to their strategic mandate. The analytical framework is organized around three core dimensions, each designed to answer specific decision-making questions:
- Therapeutic Selectivity & Molecular Architecture: The study dissects the commercial footprint across JAK1-selective inhibitors, JAK1/JAK2 dual-target agents, and pan-JAK inhibitors. This classification is not merely biochemical; it maps directly to safety profile differentiation, prescriber confidence trajectories, formulary positioning, and patient compliance dynamics. The segmentation reveals how selectivity profiles influence market share allocation, pricing resilience, and the competitive runway for pipeline assets seeking to capture adjacent indications.
- Clinical Application & Indication Expansion: Demand is analyzed across rheumatoid arthritis, atopic dermatitis, myelofibrosis, and the combined ulcerative colitis/psoriatic arthritis spectrum. The report tracks how label expansions, real-world evidence accumulation, and guideline endorsements have reshaped utilization patterns. It further examines the commercialization implications of跨界 prescribing, off-label adoption curves, and the strategic value of indication sequencing when navigating payer segmentation and specialty pharmacy distribution networks.
- Regional Commercial Dynamics: The geographic breakdown isolates pricing architecture variability, regulatory approval cadence, market access timelines, and competitive density across major commercial territories. The report evaluates how localized reimbursement frameworks, health technology assessment (HTA) requirements, and distribution channel maturity influence revenue realization. Regional analysis is structured to help multinational teams calibrate launch sequencing, prioritize market entry investments, and anticipate the velocity of generic or biosimilar erosion in mature markets.
Beyond segmentation, the study integrates supply chain vulnerability mapping, manufacturing capacity constraints, and raw material dependency analysis, drawing on observable industry signals to highlight where operational resilience will become a competitive differentiator. The report also incorporates payer behavior modeling, formulary tier positioning, and coverage determination dynamics that directly affect prescription volume conversion. Each analytical module is paired with executive-ready visualizations, scenario sensitivity tables, and strategic implication summaries tailored for cross-functional alignment between commercial, medical affairs, market access, and corporate development teams.
Competitive Architecture: Incumbents, Expansionists, and Pipeline Challengers
The JAK inhibitor market is characterized by pronounced concentration among a core group of multinational innovators, yet the competitive environment is far from static. The research maps the strategic posture, portfolio architecture, and recent commercialization moves of the principal market participants, providing a comparative lens through which clients can benchmark positioning, identify white-space opportunities, and anticipate tactical responses.
Pfizer continues to anchor a substantial share of the legacy market through its tofacitinib franchise, leveraging a broad indication footprint across rheumatoid arthritis, psoriatic arthritis, ulcerative colitis, and ankylosing spondylitis. Recent regulatory expansions into pediatric polyarticular course juvenile idiopathic arthritis and juvenile psoriatic arthritis demonstrate a deliberate strategy to extend the product lifecycle, deepen prescriber familiarity, and capture earlier intervention pathways. Incyte maintains a differentiated position through its ruxolitinib portfolio, with therapeutic applications spanning myelofibrosis, polycythemia vera, and graft-versus-host disease. The recent topical formulation approval for nonsegmental vitiligo reflects an ongoing effort to translate systemic JAK inhibition into specialty dermatology channels, broadening the commercial addressable market beyond hematology. Eli Lilly has positioned baricitinib as a multi-indication asset, capturing autoimmune and inflammatory segments including severe alopecia areata, where pediatric label expansion signals an intent to capture unmet demand in younger patient cohorts. AbbVie has aggressively expanded its upadacitinib franchise across rheumatology, dermatology, and gastroenterology, with pediatric ulcerative colitis approval reinforcing its commitment to broad therapeutic coverage and competitive density in high-prescription-volume disease states. Gilead, operating through a strategic partnership model, continues to advance filgotinib in select markets, illustrating how collaborative commercialization structures can sustain presence in mature therapeutic categories while managing risk and resource allocation. Meanwhile, emerging players such as Conatus Pharmaceuticals, backed by Roivant Sciences, are pursuing next-generation molecular designs targeting selective IRAK4/JAK1 pathways, with clinical-stage programs directed at hematologic malignancies. This pipeline activity signals a gradual diversification of the molecular target landscape, raising the strategic question of whether future market leadership will be defined by incremental selectivity optimization or by entirely new pathway combinations.
The concentration metrics underscore the entrenched nature of the incumbent base, with the top three participants commanding a substantial share of aggregate revenue and the top five entities controlling an even larger portion of market value. High concentration does not, however, equate to static market behavior. Patent expirations, safety-signal recalibration, payer formulary re-evaluations, and pipeline-driven indication displacement are introducing dynamic competitive friction. The report dissects these interactions through a competitive positioning matrix, assessing relative strength across innovation velocity, commercial execution, market access sophistication, and lifecycle management capability.
Worldwide Janus Kinase (JAK) Inhibitors Market
Beyond Headline Growth: Regulatory, Supply, and Reimbursement Undercurrents
Market trajectory is never purely a function of clinical efficacy or sales momentum. It is continuously shaped by regulatory architecture, manufacturing realities, and reimbursement policy calibration. The research integrates these structural undercurrents into a cohesive market dynamics framework, enabling clients to stress-test their strategic assumptions against observable industry pressures.
Safety monitoring and risk communication remain central to prescriber behavior and formulary management. The 2021 regulatory addition of boxed warnings across the JAK inhibitor class for cardiovascular events, malignancy risk, thrombosis, and mortality has had lasting implications for prescribing confidence, patient selection criteria, and risk mitigation protocols. The study examines how manufacturers have adapted communication strategies, how guidelines have evolved, and how payer and provider risk tolerance continues to influence utilization patterns. These safety considerations intersect directly with market concentration dynamics, as established incumbents with mature safety databases may leverage real-world evidence to stabilize prescribing, while newer entrants must navigate heightened scrutiny and longer evidence-generation timelines.
Patent lifecycle management introduces another critical variable. The impending expiration of foundational patents on legacy molecules will alter competitive economics, potentially enabling generic entry and reshaping pricing architectures in mature markets. The report maps the timing, geographic scope, and commercial implications of these transitions, providing scenario analysis that helps teams anticipate revenue erosion curves, evaluate lifecycle extension strategies, and assess the feasibility of next-generation positioning ahead of market disruption.
Reimbursement policy continues to shape utilization at scale. National coverage determinations and specialty pharmacy benefit designs directly influence patient access, copayment structures, and prescription conversion rates. The study evaluates how coverage frameworks are evolving across major markets, how prior authorization requirements are altering prescribing workflows, and how manufacturers are structuring patient support programs and market access negotiations to preserve volume while navigating cost-containment pressures.
Supply chain resilience has emerged as a non-trivial commercial risk factor. Observed constraints in active pharmaceutical ingredient availability, driven by raw material dependencies and manufacturing bottlenecks, have introduced volatility into production planning and distribution reliability. The report integrates supply-side risk mapping into the broader commercial forecast, highlighting where capacity constraints may influence market share dynamics, delay launch execution, or create pricing dislocations in underserved distribution channels.
Translating Intelligence into 2026 Strategic Action
The strategic value of this research lies in its operational translation. For portfolio and lifecycle managers, the study provides the indication-by-indication demand mapping, competitive displacement risk assessment, and patent expiration scenario modeling needed to prioritize lifecycle extension investments, pipeline advancement decisions, and combination therapy positioning. For market access and pricing teams, it delivers payer segmentation insights, coverage determination trajectories, and formulary positioning analysis that inform rebate architecture, patient access program design, and commercial negotiation strategy. For corporate development and investment teams, it offers a structured view of competitive concentration, emerging molecular differentiation, and regional growth velocity that supports acquisition screening, partnership evaluation, and capital allocation discipline.
Worldwide Juvenile Idiopathic Arthritis Treatment Market
Crucially, the report does not treat growth as a uniform phenomenon. It isolates where demand is converging across selectivity profiles, where clinical adoption is accelerating or encountering friction, and where regional commercial execution will determine whether pipeline assets translate into durable market share or remain confined to niche utilization. By aligning segmentation depth with scenario flexibility, the study enables leadership teams to move beyond retrospective hindsight and operate with forward-looking strategic clarity.
The complete Worldwide JAK Inhibitors Market research provides the full segmentation architecture, region-by-region commercial profiling, selectivity-based demand analysis, application-specific utilization tracking, competitive positioning matrices, scenario sensitivity tables, and strategic implication playbooks required to operationalize these insights. The underlying data, modeling assumptions, and cross-referenced industry intelligence are structured to support rigorous internal review, executive alignment, and investment-grade decision-making.
For stakeholders preparing for the 2026 landscape and the forecast years that follow, the full report offers the depth, granularity, and strategic framing necessary to navigate a market defined by concentration, innovation velocity, regulatory recalibration, and shifting access dynamics. To access the complete analytical framework, segmentation detail, and decision-ready intelligence, explore the full publication and accompanying executive resources.
For detailed analysis of this topic, please visit the official page: Worldwide Janus Kinase (JAK) Inhibitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Ultrasonic Scissor Market to Reach $2.26B by 2032 at 6.5% CAGR
By pmarketresearch, 2026-09-16
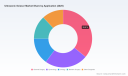
Strategic Intelligence for the Ultrasonic Scissor Market: Navigating Growth and Change Through 2032
The global surgical landscape is undergoing a profound transformation, driven by the accelerating adoption of minimally invasive techniques and the continuous refinement of energy-based surgical platforms. Within this evolving ecosystem, the ultrasonic scissor segment stands out as a critical enabler of surgical precision, tissue preservation, and procedural efficiency. As healthcare systems worldwide confront rising procedural volumes, cost containment pressures, and an expanding roster of clinical indications, executives across medical device manufacturers, hospital procurement leaders, and strategic investors require a clear, forward-looking view of market trajectories. This comprehensive Worldwide Ultrasonic Scissor Market research study is positioned to serve as that strategic compass, translating macroeconomic trends, competitive movements, and regulatory shifts into actionable intelligence for 2026 and beyond.
Understanding where the market is heading requires more than tracking headline growth figures. It demands a disciplined examination of demand drivers, product architecture evolution, regional purchasing dynamics, and the strategic calculus of entrenched incumbents and emerging challengers. The analysis that follows distills these layers into a structured, decision-ready framework. Rather than offering static snapshots, the report maps the interplay between clinical advancement, manufacturing scale, and market access pathways, equipping leadership teams with the contextual depth required to allocate capital, shape product roadmaps, and anticipate competitive responses with confidence.
Market Trajectory and the Architecture of Growth
Over the past half-decade, the ultrasonic scissor market has demonstrated a steady, structurally supported expansion. Total global revenue scaled from approximately $1,050.5 million in 2020 to an estimated $1,452.5 million in 2025, reflecting a composite annual growth pattern shaped by surgical volume recovery, technology adoption cycles, and broadening clinical utilization. Looking ahead through the 2026–2032 forecast horizon, the market is projected to continue its upward arc, reaching an estimated $2,257.2 million by the close of the period. This trajectory corresponds to a forecast compound annual growth rate of 6.5 percent, signaling a market that is maturing but still capable of generating meaningful incremental value for participants who align their strategies with underlying demand fundamentals.
Several interconnected forces underpin this growth profile. The continued migration of general, gynecologic, urologic, and specialized surgical procedures toward minimally invasive and laparoscopic approaches favors advanced energy instruments that offer controlled transection, reliable hemostasis, and ergonomic integration within constrained operative fields. Simultaneously, hospital systems and ambulatory surgical centers are increasingly prioritizing instrument durability, reprocessing economics, and single-use architectures as part of broader supply chain optimization initiatives. These operational considerations, combined with surgeon familiarity and training pathways, create a durable pull for ultrasonic scissor platforms across both established and emerging clinical settings.
Importantly, the growth environment is not uniformly distributed across all product architectures or clinical applications. The market reflects a segmented demand landscape in which handheld surgical devices and generator- or console-based systems serve distinct workflow requirements, while procedural specialties such as general surgery, gynecology, urology, and bariatric applications each present differentiated adoption curves. Understanding how these segments interact, where substitution risk exists, and which configuration aligns with specific care delivery models is essential for any organization seeking to capture sustainable share. The full report unpacks these structural nuances without reducing them to simplistic abstractions, enabling readers to assess where strategic emphasis will yield the highest return.
What the Report Delivers: Analytical Depth and Operational Utility
A market study gains strategic value only when it translates observation into execution. This research is designed from the ground up to support that transition. Rather than limiting itself to high-level revenue tables, the report assembles a multidimensional view of the ultrasonic scissor market, covering historical context, forward-looking projections, competitive positioning, and the operational levers that shape commercial outcomes. Each analytical layer is intended to inform discrete decision points, whether a manufacturer is evaluating product pipeline prioritization, a distributor is assessing regional entry timing, or a healthcare organization is benchmarking instrument adoption against clinical and financial objectives.
The analysis draws on a broad set of structured inputs, spanning market sizing across multiple time horizons, segmentation by product type and application, regional demand characterization, and market concentration metrics that illuminate the balance between incumbent dominance and emerging competitive pressure. In parallel, the report integrates qualitative intelligence on product innovation, regulatory activity, and strategic developments that influence near-term momentum. By combining quantitative structure with contextual narrative, the study enables leadership teams to move beyond static benchmarks and toward scenario-based planning.
Readers will find practical value in several areas of focus. First, the report clarifies how historical demand patterns through the base year connect to the forward forecast window, helping stakeholders distinguish cyclical fluctuations from structural shifts. Second, it examines segmentation dynamics in a way that supports product architecture decisions, pricing strategy, and channel planning, without relying on oversimplified assumptions about uniform adoption. Third, it situates regulatory activity and recent product introductions within the broader competitive landscape, offering insight into how market access timelines and device classifications can accelerate or constrain commercialization pathways. Together, these elements create a working framework that can be adapted to internal strategy sessions, investment committees, and operational planning cycles.
Competitive Landscape and Strategic Positioning
The ultrasonic scissor market is characterized by a mix of globally established medical technology firms and increasingly capable regional manufacturers. At the higher end of market concentration, the top three and top five participants collectively command a substantial share of total revenue, underscoring the strategic importance of brand equity, clinical evidence, distribution reach, and reprocessing or single-use economics. Yet the landscape is not static. New product introductions, regulatory clearances, and targeted expansion efforts continue to reshape the competitive perimeter, creating opportunities for companies that can execute on differentiation, supply chain reliability, and clinical workflow alignment.
Ultrasonic Dissector Market
Among the market’s prominent participants, Johnson & Johnson MedTech continues to leverage its HARMONIC platform, with instrument configurations such as the HARMONIC 1100 Shears and HARMONIC FOCUS+ Shears designed for precise ultrasonic dissection, vessel sealing up to 7 millimeters, and tissue transection across minimally invasive and open procedures. Medtronic maintains a strong presence through its Sonicision 7 Curved Jaw cordless ultrasonic dissection devices, which address vessel coagulation and dissection within the broader surgical energy category. Olympus Corporation contributes ultrasonic dissection and cutting instruments as part of its surgical energy portfolio, supporting endoscopic and laparoscopic workflows. Stryker Corporation participates through reprocessed HARMONIC shears and broader advanced energy offerings spanning general, pediatric, gynecologic, urologic, and thoracic applications. B. Braun Melsungen AG markets ultrasonic dissection devices within its surgical energy and minimally invasive surgery portfolio, reinforcing a comprehensive approach to procedural support.
Alongside these global players, a cohort of China-based manufacturers has been expanding its footprint with a focus on cost-competitive designs, regulatory filings, and incremental certification progress. Miconvey manufactures minimally invasive ultrasonic surgical instruments, including scissors-type ultrasonic scalpels, backed by CE, FDA, and ISO 13485 certifications. Ezisurg Medical develops the easyUS Ultrasonic Surgical System for hemostatic cutting and coagulation of soft tissues and vessels up to 5 millimeters. Reach Surgical, operating under Genesis MedTech, produces SR7 ultrasonic shears capable of sealing vessels up to 7 millimeters within an advanced energy platform that integrates ultrasonic and advanced bipolar modalities. BBT Medical specializes in scissors-type ultrasonic scalpels and harmonic scalpels for surgical applications, while Hunan Handlike Minimally Invasive Surgery Co., Ltd. offers disposable ultrasonic shears as part of its ultrasonic surgical system portfolio. These companies illustrate a broader industry trend in which regional manufacturing ecosystems are increasingly capable of contributing to global supply and product diversity, particularly as clinical and commercial requirements evolve.
Recent activity further highlights how product strategy and regulatory progress continue to shape the market’s direction. In December 2024, CMR Surgical launched an Ultrasonic Dissector for its Versius surgical robot, extending advanced energy cutting and coagulation capabilities into robotic-assisted procedures. Earlier in the same year, Genesis MedTech introduced SR7 ultrasonic shears designed to seal vessels up to 7 millimeters alongside an integrated advanced bipolar and ultrasonic energy platform. In June 2024, Hunan Handlike received FDA 510(k) clearance for its disposable ultrasonic shears within its ultrasonic surgical system, an action that not only advanced a specific product pathway but also reflected the broader regulatory framework governing ultrasonic surgical instruments under FDA product code LFL, where substantial equivalence review remains a central requirement for market access. These developments demonstrate how technological integration, platform expansion, and regulatory clearance cycles can create near-term momentum and alter competitive positioning.
Strategic Priorities for 2026 Decision-Makers
For organizations operating in or adjacent to the ultrasonic scissor market, the 2026 decision environment calls for disciplined attention to a handful of strategic priorities. First, product roadmap decisions should be anchored in clinical workflow realities rather than technology aspirations alone. The value proposition of ultrasonic shears lies in their ability to support reliable transection, vessel sealing, and tissue handling within the constraints of minimally invasive procedures, and future differentiation will increasingly depend on ergonomics, consistency, and integration with broader surgical ecosystems. Second, supply chain and instrument lifecycle strategy deserve renewed emphasis. The balance between reusable, reprocessed, and single-use formats carries implications for procurement economics, sterilization throughput, regulatory exposure, and surgeon preference, making it a central variable in commercial planning.
Worldwide Ultrasonic Scissor Market
Third, regional strategy must account for uneven adoption dynamics and varying procurement structures. Demand characteristics differ across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, and the most effective go-to-market models will be those tailored to local clinical priorities, reimbursement realities, and distributor capabilities. Fourth, competitive positioning will increasingly hinge on evidence generation, regulatory alignment, and platform versatility. As advanced energy instruments become more closely associated with robotic-assisted workflows and integrated surgical platforms, manufacturers that can demonstrate predictable performance, efficient training pathways, and compatibility with evolving procedural standards will be better positioned to defend and expand share.
Finally, leadership teams should monitor the pace and pattern of regulatory activity, not only for compliance reasons but because clearance cycles and classification pathways can influence time-to-market, competitive entry windows, and the attractiveness of specific product configurations. The interplay between technical differentiation, market access, and procurement economics will shape which players capture durable advantage as the market expands through the end of the decade.
Conclusion: Turning Market Intelligence into Strategic Advantage
The Worldwide Ultrasonic Scissor Market research study is built to support exactly that kind of informed, forward-looking decision-making. By combining historical context, forecast structure, segmentation insight, competitive profiling, and recent market-moving events, the report gives executives a reliable foundation for evaluating where value is likely to be created and how to position accordingly. The numbers alone tell only part of the story; the strategic value lies in understanding the forces behind them and the commercial choices they demand.
For organizations preparing for 2026 and the years that follow, the ability to act on granular, up-to-date intelligence can make a meaningful difference in product investment timing, market entry decisions, pricing architecture, and competitive response. To access the full dataset, regional and segment-level breakdowns, and the complete competitive and regulatory analysis, readers are encouraged to explore the complete report at the source page. There, the deeper market intelligence becomes available in a form designed to support internal strategy sessions, investment evaluation, and operational planning with precision and confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Ultrasonic Scissor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Prescription Cat Food Market to Hit $9.67B by 2032 at 6.45% CAGR
By pmarketresearch, 2026-09-16
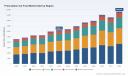
Prescription Cat Food Market Outlook 2026: Strategic Intelligence for Veterinary and Pet Care Leaders
Executive Overview
The global prescription cat food market has entered a phase of disciplined expansion, driven by a convergence of rising feline health awareness, veterinary endorsement of therapeutic nutrition, and an increasingly sophisticated pet parent demographic. For senior executives navigating the pet care ecosystem, the 2026-2032 forecast period presents a critical window to refine product portfolios, optimize supply chain resilience, and align commercial strategies with emerging clinical demand. Our latest Worldwide Prescription Cat Food Market research offers a comprehensive, data-grounded view of this trajectory, translating macro trends into actionable intelligence for portfolio planning, competitive positioning, and regional expansion.
The market has demonstrated consistent upward momentum over the past half-decade, with historical performance reflecting both post-pandemic normalization and sustained clinical adoption of veterinary diets. Looking ahead, the projected compound annual growth rate of 6.45 percent through the end of the decade signals a market that is no longer dependent on cyclical novelty but is instead anchored in steady demand for condition-specific nutrition. Revenue is expected to surpass the nine-billion-dollar threshold by the early 2030s, a milestone that underscores both the commercial maturity of the segment and the strategic importance of anticipating shifts in feline health epidemiology, formulation preferences, and distribution dynamics.
For decision-makers, this growth narrative is not merely a top-line headline. It represents a structural shift in how therapeutic cat nutrition is developed, marketed, prescribed, and distributed. Veterinary clinics, specialty retailers, and direct-to-consumer channels are each evolving their engagement models, while manufacturers are balancing formulation innovation with cost pressures in raw materials and ingredient sourcing. The strategic value of our research lies in its ability to connect these intersecting forces into a coherent playbook for 2026 and beyond.
Market Trajectory and Growth Dynamics
The historical arc from 2020 through 2025 reveals a market that recovered quickly from early volatility and then accelerated through broadened clinical adoption and stronger retail execution. Total revenue expanded steadily across that period, with notable momentum in the most recent years as consumer education around feline health conditions intensified and veterinary practices continued to recommend condition-specific diets as part of comprehensive care plans. This foundation has positioned the market to transition into a higher-growth phase, though the trajectory is not uniform across every commercial dimension.
Forecasting through 2032 suggests a market that compounds at a rate consistent with mid-single-digit expansion, reflecting a balance between underlying demand growth and operational realities such as ingredient inflation, regulatory compliance, and competitive saturation in certain categories. The projected revenue pathway indicates that while the market will continue to scale, growth will be shaped by nuanced factors including palatability improvements, formulation efficacy, veterinary endorsement strength, and the ability of manufacturers to maintain price integrity amid varying cost environments.
For strategic planners, the growth outlook carries several implications. First, the market's durability suggests that long-term investment in therapeutic nutrition is warranted, but that growth will favor companies that can differentiate through clinical credibility, channel execution, and responsive product development. Second, the pace of expansion implies that capacity planning and supply chain agility will be critical, particularly as manufacturers seek to meet demand without compromising quality or margin structure. Third, the forecast period is likely to see intensified competition for veterinary trust and consumer attention, meaning that brand positioning must be supported by clear therapeutic value propositions and consistent commercial execution.
Competitive Landscape and Brand Positioning
The prescription cat food segment remains concentrated, with a small group of leading manufacturers commanding a substantial share of market revenue. This concentration reflects the category's reliance on veterinary validation, established clinical reputations, and deep relationships with veterinary practices and specialty distribution networks. The leadership positions are held by companies that have built multi-decade portfolios around condition-specific nutrition, investing in research, formulation science, and veterinary education to reinforce their authority in therapeutic pet care.
Hill's Pet Nutrition, headquartered in Topeka, Kansas, continues to reinforce its leadership through a broad Prescription Diet portfolio that spans kidney disease, urinary health, diabetes, and gastrointestinal support. The company's recent product activity illustrates its focus on expanding therapeutic reach while sustaining core category strength. In February 2024, Hill's launched Prescription Diet Derm Complete dry cat food for dermatology support, extending its capability into skin and coat-related conditions and broadening the clinical scenarios for which veterinarians can recommend its offerings.
Royal Canin, based in Aimargues, France, maintains a strong veterinary diet presence with targeted formulations for renal support, urinary care, gastrointestinal needs, and mobility. Its November 2023 update to Renal Support formulas, designed to enhance palatability for cats, highlights the competitive emphasis on acceptance and compliance. In therapeutic nutrition, formulation performance is only part of the equation; the ability to encourage consistent consumption is equally important, especially in chronic care scenarios where adherence directly influences outcomes and customer retention.
Nestlé Purina PetCare, with its St. Louis, Missouri base, continues to advance its Pro Plan Veterinary Diets line, which includes offerings such as HA Hydrolyzed for allergen management, UR Urinary support, NF Kidney Function, and OM Overweight Management. In May 2024, Purina released an updated Pro Plan Veterinary Diets cat food portfolio with refreshed packaging, a move that signals both brand renewal and a focus on shelf impact, consumer clarity, and veterinary practice familiarity. In a category where trust is cumulative, packaging and presentation can play a meaningful role in reinforcing recognition and easing purchase decisions within retail and clinic channels.
These three leaders represent a competitive core defined by broad clinical portfolios, sustained R&D activity, and established veterinary relationships. Yet the market's structure also invites strategic nuance. High concentration does not eliminate room for differentiation; rather, it elevates the importance of execution in specific health conditions, product forms, and regional channels. Companies that can align formulation innovation with strong veterinary communication, palatability performance, and channel-specific demand generation are better positioned to capture share within an otherwise mature competitive field.
Worldwide Prescription Cat Food Market
Segment Dynamics Across Health Conditions, Product Forms, and Regions
The prescription cat food market is defined by multiple overlapping segmentation dimensions, each with its own growth logic and commercial implications. The health condition landscape reflects the clinical needs that drive veterinary recommendations and consumer purchases. Urinary health represents a major demand center, consistent with the prevalence of lower urinary tract concerns in feline medicine and the long-standing role of prescription diets in managing urinary pH, crystal formation, and hydration-related risk factors. Renal support is another substantial pillar, reflecting the importance of nutritional management in chronic kidney disease, a condition that remains highly relevant in aging feline populations. Weight management continues to draw attention as pet obesity and its downstream health implications gain recognition among both veterinarians and owners. Digestive care forms a meaningful segment as gastrointestinal sensitivities, food intolerances, and microbiome-focused nutrition become more prominent in clinical conversations. Diabetes and other condition-specific categories round out the demand picture, underscoring the breadth of therapeutic applications that contribute to overall market scale.
Product form introduces an additional strategic layer. Dry food constitutes the largest share of revenue, shaped by its convenience, shelf stability, and compatibility with routine feeding practices. Wet food holds a significant position as well, driven by its hydration benefits, higher moisture content, and appeal in cases where increased water intake is clinically desirable. Therapeutic treats represent a smaller but increasingly relevant category, often used as adjuncts for compliance, reward-based feeding, or targeted nutritional supplementation. The interplay among these forms matters because consumer preference, veterinary recommendation, and condition-specific requirements do not always align neatly. Manufacturers that can offer coherent cross-form solutions, or that can optimize one format for a specific clinical use case, may gain advantage in both practice recommendation and consumer adoption.
Regional dynamics further shape the market's competitive rhythm. North America and Europe represent substantial demand bases, supported by mature veterinary infrastructure, high pet humanization, and established prescription diet channels. Asia Pacific reflects a growing opportunity set as pet care markets expand, veterinary services modernize, and awareness of therapeutic nutrition increases. Latin America and the Middle East and Africa contribute additional demand, with growth influenced by local pet ownership trends, import and distribution frameworks, and the pace of veterinary market development. Rather than viewing these regions as uniform blocks, successful strategy requires attention to local clinical practices, channel structures, regulatory expectations, and consumer purchasing behavior. The market's breadth across regions means that a single global approach is rarely sufficient; instead, portfolio allocation and go-to-market execution must be calibrated to regional realities.
Regulatory, Supply Chain, and Operational Considerations
The prescription cat food category operates within a regulatory and operational environment that directly affects product development, labeling, marketing claims, and market access. Pet foods must comply with AAFCO nutrient profiles for complete and balanced diets, and prescription diets require veterinary substantiation. This framework reinforces the category's clinical orientation but also raises the bar for evidence support, claim discipline, and professional credibility. In practical terms, it means that product strategies must be grounded in documented nutritional rationale and that communication must be aligned with veterinary expectations. Regulatory clarity is an asset for established players, but it also creates a higher threshold for entry and differentiation for newer formulations or niche indications.
Labeling requirements add another layer of compliance discipline. FDA requirements for nutritional adequacy statements on pet food labels under 21 CFR 501.13 reinforce the importance of accurate representation and consistent quality assurance. For therapeutic products, this is especially relevant because clinicians and consumers rely on label information to make feeding decisions and to evaluate suitability for specific conditions. Companies that maintain rigorous documentation, transparent communication, and strong quality systems are better positioned to navigate these expectations while preserving brand trust.
On the supply side, ingredient dynamics remain a key operational consideration. Chicken meal prices rose 8 percent year-over-year to $1,450 per metric ton due to feed cost increases, illustrating the ongoing pressure that raw material volatility can place on formulation economics and margin management. In a category where nutritional integrity and consistent quality are non-negotiable, cost optimization cannot come at the expense of ingredient standards. This environment favors manufacturers with diversified sourcing strategies, forward-looking procurement planning, and formulation flexibility that can adapt to input cost shifts without compromising clinical performance.
Trade and market access requirements also influence regional strategy. EU Regulation (EC) No 183/2005 mandates registration of pet food establishments for imports, which affects cross-border distribution and the operational footprint required to serve European markets effectively. In parallel, recall surveillance remains a critical reputational and compliance factor. No active recalls were reported for major prescription cat food brands as of the first quarter of 2026, a positive signal for the segment's quality and process control. Maintaining that track record is essential, because even a single high-profile disruption can affect veterinary confidence, retail execution, and consumer trust across a category that depends heavily on perceived safety and clinical reliability.
Portfolio Strategy and Decision-Making for 2026
For executives planning across 2026 and the broader forecast window, the prescription cat food market rewards strategies that integrate clinical relevance, commercial discipline, and operational resilience. The most effective portfolio decisions will be informed by a clear understanding of where therapeutic demand is stable, where it is expanding, and where competitive intensity requires sharper differentiation. This means looking beyond aggregate growth and paying close attention to the relative strength of health condition segments, the adoption patterns across product forms, and the channel-specific dynamics that shape prescription diet sales.
Several strategic priorities emerge from the current environment. First, condition-specific innovation should be guided by both clinical need and practical adoption. Formulations that address meaningful health concerns are necessary but not sufficient; they must also perform well in terms of palatability, ease of recommendation, and consistency of use. Second, brand execution should reinforce veterinary trust. Given the category's reliance on professional endorsement, educational support, practice relationships, and clear therapeutic positioning can be as important as the product itself. Third, supply chain and cost management deserve active attention. Ingredient price movements, sourcing continuity, and manufacturing efficiency will influence margin outcomes and the ability to sustain competitive pricing without sacrificing quality.
Regional expansion and channel strategy also require tailored thinking. In mature markets, growth may come more from share dynamics, portfolio depth, and veterinary engagement than from broad category expansion. In faster-developing markets, the opportunity may lie in building awareness, strengthening distribution, and aligning product offerings with local clinical and consumer realities. Across all regions, the ability to translate global formulation expertise into locally relevant execution will be a defining capability.
The strategic question for 2026 is not simply whether the prescription cat food market will grow, but how companies will position themselves to capture value within that growth. This requires a view that connects market scale with segmentation logic, competitive behavior, regulatory expectations, and operational constraints. Companies that treat the category as a clinically anchored, commercially complex environment are more likely to build durable advantage than those that approach it as a routine pet food segment.
What's Inside the Report
Our Worldwide Prescription Cat Food Market research is designed to support decision-making at multiple levels, from corporate strategy and portfolio planning to competitive intelligence and regional execution. The report provides a structured analysis of historical performance and forward-looking demand, with a focus on the factors that will shape revenue, share, and competitive dynamics through 2032. It examines the market through the lenses of health condition, product form, and regional distribution, helping readers understand where demand is concentrated and how growth is likely to unfold across different commercial dimensions.
The report also includes a detailed competitive assessment of leading manufacturers, with attention to product positioning, therapeutic coverage, recent product activity, and the strategic implications of brand portfolio choices. By situating each major player within the broader market context, the analysis helps identify where concentration is highest, where differentiation matters most, and how recent launches, formula updates, and portfolio revisions may influence future competition. This competitive view is complemented by a discussion of market structure and concentration dynamics, offering context for assessing barrier levels, share mobility, and the strategic value of veterinary relationships and channel access.
In addition, the research integrates operational and regulatory considerations that affect formulation, labeling, distribution, and market entry. Topics such as nutritional adequacy requirements, veterinary substantiation expectations, ingredient cost trends, import registration requirements, and recall surveillance are addressed as part of the wider market environment. These elements are not treated as background only; they are linked directly to strategic implications for product development, cost planning, compliance readiness, and regional expansion. The report also includes practical guidance-oriented sections that help translate findings into planning assumptions, scenario thinking, and competitive response options.
Importantly, the report is structured to support both high-level strategic assessment and more detailed commercial analysis. Readers will find macro-level market trajectory, segmentation context, and competitive positioning, along with the kind of structured intelligence that can inform product roadmaps, channel strategy, and regional prioritization. The objective is to provide a credible, evidence-based foundation for decisions rather than a superficial trend summary.
How to Use This Intelligence
This research is most valuable when used as a decision-support tool rather than a static reference. For portfolio leaders, it offers context for evaluating which health conditions and product forms warrant continued investment, extension, or repositioning. For competitive strategy teams, it provides a framework for interpreting market concentration, brand differentiation, and the likely impact of recent product actions by leading manufacturers. For commercial and regional teams, it supports calibration of demand expectations, channel focus, and market-access planning in environments where regulatory and supply conditions vary.
The report is also intended to be read alongside internal data and operational knowledge. Market-level findings are most powerful when combined with company-specific sales patterns, veterinary feedback, formulation capabilities, and regional execution realities. Used in that way, the research helps clarify where external trends reinforce internal assumptions and where they suggest the need to revisit planning premises.
Conclusion
The worldwide prescription cat food market is entering a period in which growth is supported by strong clinical foundations, evolving consumer expectations, and sustained veterinary engagement, but is also shaped by competitive concentration, ingredient cost pressures, and regulatory discipline. The companies that navigate this environment successfully will be those that treat therapeutic nutrition as a strategically serious category, investing in clinical credibility, product performance, supply resilience, and channel-specific execution.
Worldwide Prescription Diet Pet Food Market
Our Worldwide Prescription Cat Food Market research provides the depth, structure, and forward-looking perspective needed to make those decisions with confidence. For leaders seeking a detailed view of segmentation dynamics, competitive positioning, regional growth patterns, and the operational factors that influence profitability and market access, the full report offers the complete intelligence foundation for 2026 planning and the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Prescription Cat Food Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cab Mounts Market to Reach $767.14M by 2032 as CAGR Hits 5.0%
By pmarketresearch, 2026-09-16
Global Cab Mounts Market Strategic Outlook 2026
Executive Summary
As heavy equipment manufacturers and automotive OEMs navigate the complexities of the 2026 industrial landscape, the stability and performance of operator cabins remain a critical, yet often overlooked, component of vehicle engineering. The Worldwide Cab Mounts Market is poised for a defined trajectory of growth, driven by stringent safety regulations, evolving operator comfort standards, and the relentless expansion of off-highway machinery sectors. PW Consulting has released a comprehensive market research study designed to equip stakeholders with the actionable intelligence needed to capitalize on these shifts. This document serves as a strategic overview, highlighting the macroeconomic currents and competitive forces shaping the industry, while underscoring the necessity of detailed analysis for precise decision-making.
The market has demonstrated resilience through recent years, transitioning from a pandemic-affected baseline to a robust growth phase. Understanding the nuances of this evolution is paramount for investors, suppliers, and procurement leaders. Our latest report dissects the ecosystem, offering a granular view of where value is being created and where risks are concentrated. The following analysis previews the key findings and structural insights contained within the full study.
Market Trajectory and Macroeconomic Performance
The global cab mounts market has exhibited steady consolidation and expansion over the past half-decade. Historical data indicates a market value of approximately 442.15 million USD in 2020, reflecting the initial baseline before recent supply chain adjustments and industrial recoveries. By 2025, the market revenue had climbed to 545.2 million USD, showcasing a consistent upward momentum despite fluctuating raw material costs and logistical challenges.
Looking forward, the forecast period from 2026 to 2032 suggests continued appreciation. The market is projected to reach 584.97 million USD in 2026, marking a significant step forward in valuation. This growth is not linear but reflects underlying shifts in demand drivers across heavy-duty trucking, construction, and agriculture. The forecast extends to a valuation of 767.14 million USD by 2032, implying a sustained compound annual growth rate of 5.0 percent over the forecast period. This trajectory signals a mature but healthy market environment where incremental innovation and replacement cycles contribute to revenue generation.
For strategic planners, these figures represent more than just top-line growth. They indicate the scale of opportunity available for companies specializing in vibration isolation solutions. The steady CAGR suggests that while the market is not experiencing explosive disruption, it offers reliable returns for players who can optimize supply chains and capture market share through superior product performance. However, the aggregate numbers only tell part of the story. The distribution of this value across regions, types, and applications contains the specific intelligence required for targeted expansion.
Segmentation Dynamics and Operational Drivers
The market structure is defined by distinct segmentation splits that reveal where the heaviest demand resides. In terms of product type, the market is dominated by traditional elastomeric solutions, with Rubber Cab Mounts holding the largest share of revenue. Polyurethane Cab Mounts and Hydraulic Cab Mounts constitute the remainder, each serving specific niche requirements related to damping characteristics and load handling. The choice between these materials often hinges on the specific operational environment of the machinery, ranging from standard road vibrations to extreme shock loads in mining and construction.
Engine Mounts Market
Application-wise, the Heavy-Duty Trucks segment represents the most significant portion of market demand. This is followed by Construction Equipment and Agricultural Machinery, which together form the backbone of off-highway machinery consumption. The Others category includes specialized vehicles and equipment that require custom isolation solutions. Understanding the revenue contribution of each application is vital for manufacturers deciding where to allocate R&D resources. For instance, the growth in agricultural machinery may be tied to seasonal cycles and regional farming policies, whereas construction equipment demand correlates with infrastructure spending.
Geographically, the market is spread across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique challenges regarding regulatory compliance, such as ROPS (Roll Over Protective Structures) testing requirements, and varying levels of industrialization. The Asia Pacific region, in particular, reflects the massive scale of manufacturing activity, while North America and Europe maintain high standards for operator comfort and noise reduction. The specific revenue breakdown per region highlights where the most lucrative partnerships and distribution networks exist.
Beyond simple categorization, the market dynamics are influenced by several critical factors. Raw material composition plays a significant role, as cab mounts primarily consist of rubber-to-metal bonded components using natural or synthetic elastomers. Fluctuations in steel or elastomer pricing can impact margins significantly. Furthermore, the regulatory environment is tightening, with cab mounts in construction and agricultural equipment needing to support compliance with ROPS testing through appropriate vibration isolation and load handling characteristics.
A major macro trend driving demand is the requirement for improved operator comfort. There is an increasing focus on reduced whole-body vibration exposure and lower noise levels in off-highway machinery to enhance safety and productivity. This shifts the value proposition from purely functional isolation to ergonomic and health-centric engineering, creating opportunities for advanced mounting solutions that offer superior performance in these areas.
Competitive Landscape and Key Players
The market concentration indicates a moderately fragmented environment. The Cr3 percent stands at 31.45 percent, and the Cr5 percent reaches 48.9 percent. This suggests that while there are dominant players, there is still ample room for mid-sized and specialized firms to compete effectively, particularly in niche segments or regional markets. The competitive landscape is characterized by established global manufacturers with strong engineering capabilities and extensive distribution networks.
Several key companies define the current industry standards. Trelleborg AB, headquartered in Sweden, offers high-quality Cab Mounts with superior anti-vibration performance. Their portfolio includes MDS high-efficiency mounts for off-highway vehicles such as compactors, excavators, skid steer loaders, articulated dump trucks, and wheel loaders in construction and mining equipment. Notably, Trelleborg maintains a 2025 Industrial Products Catalogue covering their full anti-vibration portfolio, signaling a commitment to comprehensive product documentation and availability.
Link Manufacturing, based in the USA, positions itself as a world leader in cab suspensions, having supplied over two million OEM cab suspensions. Their Cabmate air suspension systems replace solid rear cab mounts with air springs and shocks for Class 7/8 trucks, agriculture sprayers, emergency vehicles, military vehicles, and terminal tractors. This technology provides a smoother ride, reduced vibration, and lower maintenance, distinguishing them in the heavy-duty truck segment.
GMT Rubber-Metal-Technic Ltd in the United Kingdom manufactures cone mounts often used as cab mounts for high shock loads in heavy-duty machinery, off-road vehicles, construction, and industrial equipment. They provide progressive stiffness, overload protection, and various rubber compounds tailored to environmental conditions, addressing the needs of extreme operating environments. Meanwhile, Aplicaciones Mecánicas del Caucho S.A. (AMC-MECANOCAUCHO) in Spain produces Cab Mounts consisting of two metal parts bonded to highly resilient rubber for vibration isolation in agricultural tractors, construction equipment, and off-road vehicles. They support ROPS testing and offer various hardnesses and load capacities with corrosion protection, aligning closely with regulatory demands.
Parker LORD, formerly LORD Corporation, provides Viscous Cab Mounts and Fluidlastic Cab Mounts combining elastomeric and viscous fluid damping for superior vibration and noise control in off-highway operator cabs and platforms on construction, mining, and heavy equipment. Their focus on fluid damping technology offers a different mechanical approach compared to standard elastomers. Hutchinson SA in France supplies standard and custom cab mounts and body mounts as vibration isolators for on-highway and off-highway trucks, tractors, and machinery, leveraging a broad global footprint. Finally, SumiRiko (Sumitomo Riko Company Ltd) in Japan manufactures anti-vibration rubber products including body mounts and related isolation components applicable to vehicle and machinery cabs through its global operations including SumiRiko Ohio and Tennessee.
Recent industry activities highlight the ongoing commitment to product development and catalog maintenance. For example, in 2025, Trelleborg AB released an updated Industrial Products Catalogue covering their full anti-vibration portfolio including cab mounts. Such moves indicate that competitors are actively refining their offerings and communication strategies to capture market share. The full report provides a detailed competitive matrix, analyzing strengths, weaknesses, and strategic moves beyond these public summaries.
Strategic Implications for 2026 Decision Making
For executives and strategic planners, the data points outlined above serve as a foundation for broader strategic decisions. The projected growth to 767.14 million USD by 2032 suggests that the cab mounts market remains a viable arena for investment and expansion. However, the diversity in segmentation splits means that a blanket strategy is unlikely to succeed. Companies must identify which type, application, or region offers the highest marginal return based on their specific capabilities.
The moderate market concentration suggests that consolidation opportunities may exist, but organic growth through superior product performance remains a viable path. With the Cr5 percent at 48.9 percent, the top five players control a significant portion of the market, implying that new entrants or smaller players must differentiate through specialized technology, such as advanced fluid damping or specific compliance certifications like ROPS.
Supply chain considerations regarding raw materials like natural or synthetic elastomers and steel also require attention. Volatility in these inputs can erode margins, making strategic sourcing and long-term supplier relationships critical. Furthermore, the emphasis on operator comfort and safety regulations means that product development cannot stagnate. Manufacturers must invest in R&D to meet the evolving demands for reduced whole-body vibration and noise levels.
Unlock the Full Intelligence Package
This overview provides a high-level synthesis of the Worldwide Cab Mounts Market, highlighting the growth trajectory, segmentation structure, and competitive intensity. However, the specifics required for actionable strategy—such as exact regional revenue shares, precise application breakdowns, and detailed company profiles—are reserved for the full research document. To navigate the 2026 landscape with confidence, stakeholders need the complete dataset.
Worldwide Cab Mounts Market
PW Consulting's full report offers deep dives into pricing models, supply chain vulnerabilities, regulatory impacts, and granular forecasting that goes beyond the aggregate figures presented here. We invite you to access the complete study to secure the comprehensive intelligence necessary for informed decision-making. The detailed segmentation data and competitive analysis contained within will allow you to pinpoint opportunities and mitigate risks with precision.
For access to the full Worldwide Cab Mounts Market research and to download the complete dataset, please visit the PW Consulting research portal. Ensure your organization is equipped with the deepest market insight available for the upcoming forecast period.
For detailed analysis of this topic, please visit the official page: Worldwide Cab Mounts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 3D Scanning Wind Lidar Market Hits $145M in 2025, Projected 7.85% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Wind Energy Transition: Inside the Worldwide 3D Scanning Wind Lidar Market
The global transition toward renewable energy infrastructure is no longer a question of ambition, but of precision. As wind farm developers, engineering firms, and meteorological agencies navigate increasingly complex site conditions, the demand for high-fidelity atmospheric data has elevated 3D scanning wind lidar from a niche research tool to a critical asset in project lifecycle management. Our latest Worldwide 3D Scanning Wind Lidar Market report provides a comprehensive strategic roadmap for executives, investors, and technology leaders preparing for the 2026 to 2032 forecast horizon. This article outlines the core dynamics shaping the sector, demonstrates the analytical depth of our research, and illustrates how the full report can directly inform capital allocation, product positioning, and competitive intelligence decisions.
The Macro Trajectory: Sustained Growth Anchored by Measurement Precision
The market has demonstrated consistent expansion across the historical review period, with total revenue climbing from $105.0 million in 2020 to $145.0 million by 2025. This trajectory reflects a broader industry shift toward data-driven site selection, reduced measurement uncertainty, and accelerated permitting timelines. Looking ahead, the forecast period through 2032 positions the market for continued expansion, with projected valuations scaling past $246 million by the end of the cycle. The compound annual growth rate of 7.85% underscores a structural rather than cyclical growth pattern, driven by sustained capital deployment in onshore and offshore wind development, tighter regulatory expectations for resource validation, and the maturation of scanning lidar hardware that now delivers repeatable, high-resolution wind field mapping.
Wind Lidar Market
For enterprise decision-makers, these figures are more than historical markers or projection lines. They represent the commercial envelope within which product roadmaps, partnership strategies, and regional entry plans must be calibrated. Understanding where volume concentrates, how pricing architectures evolve, and which deployment models are gaining operational traction will determine whether organizations can capture margin expansion or remain exposed to commoditization pressure.
Segmentation Realities Shaping Commercial Strategy
The commercial landscape of 3D scanning wind lidar is defined by three structural dimensions that collectively dictate procurement behavior, engineering requirements, and sales motion design. Each dimension carries distinct adoption drivers, performance thresholds, and integration challenges that separate early movers from late followers.
- Regional demand architectures: Market volume is distributed across mature wind markets with established measurement protocols and emerging development corridors where site characterization is accelerating. Procurement patterns differ materially by region, reflecting variations in regulatory frameworks, grid interconnection timelines, local content expectations, and the maturity of service ecosystems. Strategic positioning requires more than top-line allocation awareness; it demands insight into which territories are transitioning from pilot deployments to standardized multi-unit rollouts.
- Deployment model divergence: Ground-based scanning configurations dominate operational practice by a significant margin, reflecting their versatility in complex terrain, flexibility in campaign design, and compatibility with multi-season measurement requirements. Complementary deployment forms, including nacelle-integrated and buoy-mounted architectures, address specialized use cases where continuous turbine-adjacent measurement or offshore platform constraints demand alternative form factors. The interaction between these deployment categories shapes service contracts, calibration cycles, and the value proposition of hybrid measurement campaigns.
- Application-driven purchasing logic: Resource assessment remains the foundational demand driver, as developers require defensible wind field characterization to secure financing and optimize turbine layout. Operations-focused deployments are expanding as operators seek condition-aware performance monitoring and wake interaction insights. Meteorological research applications contribute a specialized but technically demanding demand layer, often setting the benchmark for accuracy, data density, and long-term reliability that commercial buyers subsequently expect.
These segmentation dynamics cannot be interpreted in isolation. The interplay between regional procurement cycles, deployment configuration preferences, and application-specific certification expectations creates a matrix of opportunity that rewards firms with modular product strategies, clear use-case positioning, and localized technical support capabilities.
Competitive Landscape: Differentiated Capabilities in a Consolidating Field
Market concentration metrics indicate a moderately consolidated environment, where a defined group of established manufacturers holds a substantial share of revenue, yet meaningful differentiation remains possible through measurement architecture, software integration, and campaign-level service design. The strategic implications for both incumbents and entrants hinge on how value is captured across hardware, validation, and downstream data services.
Several organizations define the current competitive frontier through distinct technical and commercial positioning:
- Vaisala continues to anchor its offering around the WindCube Scan series, emphasizing dual scanning capabilities for 3D wind field measurement, resource assessment, and offshore wind campaigns. Its recent product update focused on improved performance for wind energy and meteorological applications, reinforcing a strategy centered on measurement reliability and cross-sector applicability.
- ZX Lidars has built a reputation around ground-based scanning systems such as the ZX 300 series for accurate remote wind measurements. Its September 2025 launch of the ZX 300e ground-based wind lidar system, with IEC classification up to 200 metres following independent testing, illustrates the growing commercial weight of standardized validation and the competitive advantage of documented compliance.
- Movelaser contributes a programmable scanning approach through its Molas 3D Scanning Wind LiDAR System, targeting high-accuracy wind measurements in wind energy and adjacent applications. The emphasis on configurable scanning modes reflects a market preference for adaptability across terrain types and campaign objectives.
- Halo Photonics, now part of Lumibird , develops coherent pulsed Doppler wind lidar systems, including the Streamline series, suitable for profiling and scanning applications. Its technical lineage in Doppler measurement continues to influence expectations for signal quality and atmospheric sensitivity.
- ZATA offers the VWL 3D Scanning Doppler LiDAR for atmospheric wind profile measurement, leveraging pulse laser Doppler shift techniques. Its presence highlights the broader ecosystem of providers addressing atmospheric monitoring and wind profiling with specialized optical architectures.
- Leonardo provides the SKIRON3D high-end Doppler lidar system designed for 3D wind shear, gust, and turbulence monitoring, with applications spanning aviation and potential wind energy hazard detection. This high-performance positioning demonstrates how scanning lidar influence extends beyond pure resource assessment into safety-critical and hazard-aware operational contexts.
- Windar Photonics focuses on nacelle-mounted and scanning lidar solutions tailored to wind energy applications, illustrating how deployment-specific design is becoming an increasingly visible competitive axis.
The strategic question for market participants is not simply who leads today, but which capability bundles will define purchasing preference in 2027 and beyond. Product performance, certification readiness, calibration logistics, software interoperability, and service responsiveness collectively determine whether a vendor is viewed as a measurement instrument supplier or a partner in de-risking project development.
Industry Dynamics: Validation, Offshore Expansion, and Component Evolution
Three concurrent dynamics are reshaping how value is created and captured across the 3D scanning wind lidar market. First, measurement confidence is increasingly institutionalized through independent testing and compliance pathways. Wind lidar systems intended for wind energy applications are undergoing rigorous independent evaluation to ensure measurement accuracy and classification alignment with IEC standards. As demonstrated by recent product milestones in the sector, IEC classification is no longer an abstract technical benchmark; it is becoming a procurement prerequisite that influences bankability, risk modeling, and vendor selection criteria. Organizations that treat validation as a core product attribute rather than a post-development formality are gaining structural advantage in tenders and multi-vendor evaluation processes.
Second, offshore wind expansion is accelerating demand for scanning lidar capable of 3D wind field mapping and, in certain configurations, dual lidar setups for enhanced resource assessment. Offshore measurement challenges—complex boundary layer behavior, limited fixed measurement infrastructure, and the cost of met mast deployment—are pushing developers toward remote sensing solutions that can deliver spatially rich data across extended campaign durations. This shift is expanding the technical expectations placed on scanning architectures, data processing pipelines, and offshore deployment logistics.
Worldwide 3D Scanning Wind Lidar Market
Third, the underlying component ecosystem continues to evolve in ways that affect cost structures, performance ceilings, and supply chain resilience. Core systems increasingly rely on eye-safe fiber lasers operating around 1550nm, paired with associated photodetectors and optical assemblies. Advances in these components influence not only measurement range and signal fidelity, but also system reliability, maintenance intervals, and the economic feasibility of extended offshore or remote onshore deployments. Manufacturers that secure access to robust optical and laser component supply chains, and that design around serviceability and calibration durability, are better positioned to protect margins and delivery timelines.
What the Full Report Delivers: Operational Intelligence for 2026 Decision-Making
The complete Worldwide 3D Scanning Wind Lidar Market report translates these dynamics into an actionable decision framework. It is designed for teams that need to move from market awareness to executable strategy, with analytical depth sufficient to support product planning, investment review, and competitive response. The report provides a structured examination of market sizing and forecast behavior across the full historical and projection window, with particular attention to the inflection points and growth drivers most relevant to mid-cycle planning. Rather than presenting static totals, the analysis connects revenue trajectories to the development pipelines, measurement campaigns, and procurement rhythms that generate demand.
Beyond top-line sizing, the report delivers a detailed segmentation architecture that clarifies how regional demand patterns, deployment model adoption, and application-driven purchasing behavior interact. This enables readers to identify where commercial concentration is forming, which segments are most exposed to certification-driven consolidation, and where deployment flexibility can be monetized through differentiated service offerings. The analysis also maps competitive positioning across the principal manufacturers, examining product lineage, recent launches, validation milestones, and the strategic implications of recent moves in the sector. This competitive review is structured to help executive teams assess which capabilities are becoming table stakes and where durable differentiation can still be built.
Industry context is integrated throughout, ensuring that macroeconomic and technical signals are interpreted through a commercial lens. The report addresses how offshore wind momentum, compliance and classification expectations, and component-level evolution are reshaping procurement criteria and supplier evaluation. It further explores the operational realities of deployment, including the logistics of ground-based scanning campaigns, the trade-offs inherent in nacelle and buoy-mounted configurations, and the growing importance of data processing, calibration reliability, and long-term support models.
For corporate strategists, the report functions as a structured input to multiple decision pathways. Product leaders can use the segmentation and competitive maps to prioritize feature development, certification investment, and deployment-specific variants. Commercial teams can align go-to-market design with the regions and applications where measurement requirements and project timelines are converging most rapidly. Investment and partnership teams can evaluate which segments are attracting sustained demand and where supply chain or service capabilities are likely to become the binding constraint on growth.
Why This Report Matters for 2026 and Beyond
The 2026 planning cycle will reward organizations that can connect market growth to segment-level realism. A 7.85% compound growth path over the forecast horizon is meaningful only when paired with clarity on where volume is forming, which deployment models are becoming standard, how certification is reshaping vendor selection, and where offshore measurement requirements are creating premium demand for 3D scanning capability. The market is large enough to support multiple business models, but selective enough that undifferentiated hardware offerings will face increasing pressure on price and procurement cycle time.
Access to the complete report provides the missing granularity required to act with confidence: detailed structural analysis, provider positioning, recent development context, and the segmentation logic needed to translate forecast data into operational decisions. For enterprises operating in wind resource assessment, turbine operations, meteorological research, or lidar hardware and services, this research offers a single, coherent reference point for understanding where the market is heading and how to position for it.
The full Worldwide 3D Scanning Wind Lidar Market report is now available. Readers seeking the complete segmentation analysis, forecast detail, competitive profiles, and strategic recommendations can access the full research package to support 2026 planning and longer-term market strategy.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Scanning Wind Lidar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Ferrite Cable Cores Market Hits $750M in 2025, Forecast 5.23% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Worldwide Ferrite Cable Cores Market
As global electrification and data transmission speeds accelerate, the ferrite cable cores market stands at a critical inflection point. For executives making capital allocation, supply chain, and R&D decisions in 2026, understanding the trajectory of this specialized EMI suppression sector is no longer optional—it is a strategic imperative. The Worldwide Ferrite Cable Cores Market research report provides a comprehensive, data-driven framework to decode market arithmetic, competitive maneuvering, and structural supply constraints that will define the next seven years of industry growth.
This article previews the analytical architecture of the full study, highlighting the macro momentum, competitive dynamics, and operational realities that corporate strategists must internalize before committing to product roadmaps or vendor partnerships.
Market Trajectory and Structural Growth Drivers
The market has demonstrated resilient expansion over the historical review period, moving from an estimated 580.45 million USD in 2020 to a projected 750.0 million USD in 2025. This growth has been propelled by the irreversible miniaturization of electronic assemblies, the proliferation of high-speed data interfaces, and the tightening of electromagnetic compatibility standards across consumer, industrial, and automotive domains. The base year establishes a clear baseline of demand elasticity tied to device density rather than unit volume alone.
Looking toward the forecast horizon of 2026 through 2032, the sector is positioned to compound at a steady rate, with revenue expected to breach 787.4 million USD in 2026 and continue scaling toward over 1 billion USD by the early 2030s. The 5.23 percent CAGR reflects a mature yet structurally expanding market, where growth is less dependent on headline adoption cycles and more anchored in the continuous need for noise suppression across expanding cable networks. For decision-makers, this trajectory signals that ferrite cable cores are transitioning from a commodity-adjacent component to a performance-critical element in system-level electromagnetic integrity design.
The revenue progression underscores a market that rewards foresight. Early-stage planning in 2026 must account for both the volume uplift driven by electrified transport and high-bandwidth communications, as well as the margin pressure introduced by raw material volatility and regional trade dynamics. Understanding where demand concentrates and how pricing power shifts across the value chain will separate organizations that merely absorb cost increases from those that reposition their portfolios ahead of the curve.
Core Report Scope and Actionable Intelligence
The full research study is engineered to move beyond top-line projections and into the operational granularity that procurement, engineering, and strategy teams require. It delivers a structured dissection of the market across three primary analytical lenses: product typology, end-use application, and geographic distribution. By isolating how cylindrical and sleeve cores, snap-on and split cores, flat and ribbon cable cores, and other specialized formats contribute to total market value, the report enables precise portfolio alignment with high-growth segments without relying on generalized industry narratives.
The application breakdown maps revenue contribution across consumer electronics, automotive electronics, industrial automation, IT and telecommunications, and medical and other sectors. This mapping is essential for companies evaluating market entry, capacity expansion, or customer vertical prioritization. Each application carries distinct qualification requirements, volume profiles, and price sensitivity thresholds, and the study contextualizes how these variables intersect with long-term demand forecasting.
Geographically, the research delineates regional market structures, capturing how local manufacturing footprints, trade flows, and regulatory environments shape demand and supply patterns. Rather than presenting static snapshots, the analysis integrates historical volatility and forward-looking policy trajectories to help executives anticipate where regional opportunities will open or contract. The report also incorporates competitive benchmarking, pricing architecture, and regulatory overlay, providing a multi-dimensional view that supports scenario planning rather than point forecasts.
Practitioners will find the study particularly valuable for its integration of supply-side realities with demand-side growth. By linking material sourcing dependencies, certification pathways, and lead-time extended conditions to market sizing, the report offers a pragmatic lens for building resilient sourcing strategies and realistic production calendars.
Competitive Landscape and Strategic Positioning
The ferrite cable cores market exhibits moderate concentration, with the top three firms accounting for approximately 38.45 percent of total revenue and the top five capturing roughly 52.12 percent. This structure indicates a competitive arena where established multinationals hold meaningful share, but specialized manufacturers and regional players retain the ability to command niche positioning through material innovation, application-specific certification, and localized service capabilities.
Leading participants such as TDK Corporation and Murata Manufacturing Co., Ltd. continue to anchor the market with broad portfolios spanning clip-on, toroidal, and snap-on configurations tailored for EMI suppression across consumer electronics, automotive, and industrial cable assemblies. Their scale enables sustained investment in high-permeability formulations and high-frequency performance, which is increasingly relevant as data rates climb and cable architectures become more densely packed. Laird Technologies, operating under its advanced materials heritage, competes with snap-on and cable core solutions designed for high-frequency noise suppression in power cords, USB cables, and automotive wiring harnesses, emphasizing qualification depth and application reliability.
Fair-Rite Products Corp. has carved a distinct position by specializing in ferrite cores, rods, and snap-on assemblies for EMI and RFI suppression across telecom, medical, and aerospace cable assemblies, where stringent validation and material consistency carry outsized weight. Ferroxcube, part of the Yageo Company ecosystem, contributes ferrite cable cores and toroidal cores focused on power line filtering and EMI suppression in industrial and consumer electronics, while Vacuumschmelze GmbH & Co. KG brings high-performance ferrite core expertise to automotive, renewable energy, and telecommunications applications where thermal and frequency performance thresholds are demanding.
Ferrite Cores Market
Mitsubishi Materials Corporation and Samsung Electro-Mechanics reinforce the Asian manufacturing base with ferrite cores and EMI suppression components targeting mobile devices, PCs, and automotive cables, aligning component performance with the rapid product cycles of consumer and automotive electronics. Sunlord Electronics focuses on cost-effective ferrite cable cores and snap-on filters for consumer electronics and data cables, appealing to value-sensitive volume segments. Epcos AG, as aTDK subsidiary, adds specialized capability in ferrite cores for EMI suppression in power supply cables and high-speed interfaces, extending the portfolio breadth of larger industrial groups.
Recent corporate activity illustrates how competition is shifting from pure volume toward performance differentiation. In October 2025, TDK Corporation introduced new high-permeability ferrite snap-on cores for 5G and automotive Ethernet cables, emphasizing improved noise suppression up to 10 GHz. In June 2025, Fair-Rite Products Corp. released an updated catalog featuring 31-material ferrite cores optimized for USB4 and PCIe Gen5 cable EMI filtering, reflecting the market's migration toward higher data-rate standards. In March 2025, Laird Performance Materials achieved AEC-Q200 qualification for automotive-grade ferrite cable cores for EV charging cables, a milestone that underscores the increasing importance of automotive reliability certifications in securing design wins. In November 2024, Murata Manufacturing showcased compact ferrite cores for high-speed data cables at Electronica 2024, reinforcing continued investment in form-factor reduction and integration-friendly designs.
For strategists, these developments point to a market where material science, certification readiness, and application-specific engineering now determine share shifts more than broad distribution reach alone. Companies that can align product attributes with fast-emerging cable standards and automotive electrification requirements will capture disproportionate value in targeted segments.
Supply Chain, Regulatory, and Pricing Dynamics
Beyond demand and competition, the operational environment for ferrite cable cores is shaped by material sourcing concentration, trade policy, and regulatory compliance. Ferrite core production depends on iron oxide, manganese, and zinc, with sourcing heavily concentrated in China, which accounts for more than 80 percent of global supply. This dependency creates structural sensitivity to raw material availability, logistics disruptions, and regional production policy shifts. For companies building multi-year procurement plans in 2026, mapping exposure to these inputs is essential to avoid margin erosion and production delays.
Trade dynamics further complicate sourcing and cost planning. US tariffs on Chinese ferrite components increased to 25 percent under Section 301 in 2024, directly affecting import costs for cable core assemblies and compressing the economics of cross-border procurement strategies. Organizations that previously relied on centralized Asian sourcing must now evaluate regionalization, dual-sourcing, or localized assembly models to protect cost structures and delivery reliability.
Worldwide Ferrite Cable Cores Market
Regulatory requirements add another layer of complexity. The EU RoHS Directive 2011/65/EU restricts lead and cadmium in ferrite cores to below 0.1 percent by weight for all electronics cables, maintaining compliance as a continuous operational requirement rather than a one-time certification event. This standard influences material selection, supplier qualification, and documentation processes, especially for multinational product lines that must satisfy multiple jurisdictional requirements simultaneously.
Pricing pressure has become more visible as input constraints intersect with demand momentum. The average price of snap-on ferrite cores rose 12 percent year-over-year to a range of roughly 0.45 to 1.20 USD per unit, driven by raw material shortages and tighter availability. This increase affects not only component cost but also the broader economics of cable assembly manufacturers, who must balance price pass-through with competitive positioning. Lead times have also extended, with NiZn ferrite cores reaching 20 to 24 weeks amid surging demand for EV and data center cables. Such extended lead times alter inventory planning, engineering validation cycles, and time-to-market assumptions, making supply visibility a strategic asset rather than an operational footnote.
Why This Research Matters in 2026
In 2026, the ferrite cable cores market will reward organizations that combine demand foresight with supply discipline. The convergence of high-speed data standards, automotive electrification, and stringent electromagnetic compliance requirements is expanding the addressable need for effective noise suppression, but it is also intensifying competition for materials, certifications, and qualified manufacturing capacity. The strategic question is no longer whether the market will grow, but how to position within that growth in a way that preserves margin, agility, and customer relevance.
This research provides the analytical scaffolding to answer that question. It equips leadership teams with a structured view of where revenue is accumulating, how competitive advantages are being built, and which external pressures will most affect cost and availability. By linking market sizing to material realities, trade exposure, and product differentiation trends, the study enables more confident decisions on capacity planning, vertical focus, supplier selection, and R&D prioritization.
For executives seeking to move from observation to action, the full report delivers the detail required to translate macro momentum into executable strategy. The complete analysis, including granular segmentation, regional dynamics, competitive benchmarking, and forward-looking scenario considerations, is available through the official market research page, where organizations can access the full intelligence needed to guide 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Ferrite Cable Cores Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Lapis Lazuli Pendant Market to Hit $235.91M by 2032 with 5.86% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Lapidary Renaissance: Navigating the 2026 Worldwide Lapis Lazuli Pendant Market
Executive Overview
Precision Decision-Making in a Niche Luxury Segment
The global lapis lazuli pendant market embodies a unique intersection of historical prestige, artisanal craftsmanship, and modern luxury jewelry demand. As corporate strategy teams navigate an increasingly complex landscape defined by shifting supply chains, evolving consumer preferences for ethically sourced gemstones, and regional trade realignments, access to granular, forward-looking market intelligence is no longer optional.
PW Consulting has published a comprehensive strategic assessment of the Worldwide Lapis Lazuli Pendant Market, designed specifically to equip executive leadership, supply chain directors, and category managers with actionable intelligence for 2026 planning cycles. This introductory analysis previews the core structural insights of the full report, demonstrating the analytical rigor applied while highlighting exactly where enterprise-grade strategic depth awaits. For decision-makers who require precise segmentation mapping, channel profitability benchmarks, and competitive positioning matrices, the complete publication delivers the quantified frameworks necessary to allocate capital, adjust sourcing strategies, and capture share with confidence.
Macro Trajectory and Structural Momentum
Over the historical analysis window from 2020 through 2025, the worldwide lapis lazuli pendant market has demonstrated consistent valuation expansion, moving from a baseline above 118 million USD to a 2025 revenue milestone exceeding 158 million USD. The compound annual growth rate across the broader measurement horizon settles at approximately 5.86 percent, signaling an industry that is expanding at a disciplined but sustained pace rather than experiencing speculative volatility.
Forward-looking projections extend through 2032 and reveal a market that will surpass the 235 million USD threshold by the terminal forecast year. Notably, the near-term trajectory includes measurable inflection points as strategic investments in artisanal supply integration, digital retail channels, and premium metal-setting categories compound. The full study dissects these inflection points across multiple analytical lenses, providing procurement leaders and brand strategists with the precise timing indicators needed to synchronize inventory planning, production scaling, and regional market entry.
The Competitive Ecosystem and Strategic Positioning
The lapis lazuli pendant landscape is populated by a diverse cohort of enterprises whose operational models span direct mine-to-market sourcing, wholesale sterling silver manufacturing, and high-end in-house goldsmithing. Understanding this competitive architecture is essential for brands evaluating partnership opportunities, benchmarking pricing structures, and anticipating supply-side pressure points.
- Family-owned importers that maintain direct oversight of overseas sourcing operations, emphasizing authenticity and traceable stone provenance.
- Leading Indian wholesale manufacturers specializing in 925 sterling silver lapis lazuli pendants designed for export and retail distribution.
- Direct exporters operating from the Badakhshan mining region, supplying both raw material and finished pendant formats to global buyers.
- Online wholesale suppliers positioned around ethically sourced, 100 percent genuine stone guarantees for U.S. retail and resale networks.
- Handcrafted jewelry producers and custom-order wholesalers offering competitive-rate, high-grade sterling silver collections tailored to boutique retail storefronts.
- Global artisan platforms that aggregate traditional and contemporary pendant designs across multiple cultural sourcing regions.
- European high-end manufacturers operating in-house goldsmith workshops, producing premium collections with strong regional craftsmanship differentiation.
The full market study evaluates these actors through competitive intensity frameworks, vertical integration analyses, and sourcing-model comparisons. Rather than presenting a static directory, the report maps how each corporate archetype influences pricing benchmarks, channel access, and customer perception. Procurement and brand strategy teams will find precise guidance on where supplier consolidation dynamics are emerging, which sourcing models command premium positioning, and how artisanal versus industrial production pathways shape margin profiles.
Distribution Architecture and Channel Interplay
Distribution strategy in the lapis lazuli pendant market is defined by a multi-channel ecosystem where specialty jewelry stores, online e-commerce platforms, and departmental retail formats each play distinct roles in buyer acquisition, basket composition, and brand positioning. The interplay between these channels creates opportunities for differentiated go-to-market approaches, especially as luxury consumers increasingly value transparency, provenance narratives, and curated product storytelling.
Worldwide Keychain Pendant Market
Online commerce has become a critical growth vector, enabling manufacturers and wholesalers to reach global audiences, shorten discovery cycles, and scale transaction volumes with relatively low physical footprint requirements. Specialty jewelry stores, meanwhile, maintain a powerful role in trust-building for higher-value purchases, offering tactile engagement, expert guidance, and brand experience environments that digital channels alone cannot fully replicate. Departmental and broader retail formats contribute complementary reach, particularly for entry-level and gift-oriented segments within the pendant category.
The detailed report assesses how these channels interact across pricing tiers, customer acquisition costs, and regional adoption curves. For enterprise planners, the strategic question is no longer whether to participate across channels but how to balance channel investment, manage channel conflict, and align inventory allocation with the demand characteristics of each consumer segment.
Regional Dynamics and Supply-Side Realities
The lapis lazuli pendant market operates within a complex geographic footprint shaped by mining origins, transit corridors, import regulations, and regional consumer demand patterns. This structural complexity makes regional intelligence indispensable for sourcing strategy, tariff modeling, and demand forecasting.
Afghanistan remains a foundational supplier region, with Badakhshan mines historically associated with the world’s most recognized lapis lazuli output. Recent industry analysis indicates that jewelry-related exports from the region are projected to grow significantly by 2026, reinforcing the economic role of lapis supply chains for local production ecosystems. At the same time, the Lapis Lazuli Corridor continues to function as an important international transit route linking Afghanistan to Turkey through Central Asia, the South Caucasus, and regional logistics nodes, supporting mineral and finished product export flows.
On the regulatory front, importers of colored gemstones and set jewelry into the United States have had to contend with new tariff exposures and origin-verification requirements. These shifting compliance dynamics directly affect landed costs, sourcing timelines, and supplier selection criteria for lapis lazuli pendants entering key consumer markets.
North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each contribute materially to demand, supplier access, and channel behavior. The complete study provides decision-makers with the analytical scaffolding needed to interpret these regional patterns without relying on imprecise generalizations. Strategic readers will gain explicit visibility into how regional concentration, sourcing exposure, and channel maturity interact to influence both margin potential and market-entry risk.
The 2026 Decision Catalyst: Why This Report Matters Now
The full market study is structured to support real-world strategic decisions rather than abstract observation. It includes demand drivers, supply-side constraints, pricing behavior, material quality benchmarks, artisanal authentication considerations, regulatory flux assessments, and channel performance indicators. Each component is designed to feed directly into planning workflows, from category management and sourcing strategy to brand positioning and risk mitigation.
For executives, this is a year when disciplined market intelligence becomes a competitive differentiator. Tariff regimes are adjusting, artisanal sourcing narratives are gaining consumer attention, and digital distribution is reshaping how pendant buyers discover and purchase. A 5.86 percent growth trajectory is meaningful, but its strategic value depends on understanding where growth is most durable, which supplier models are gaining advantage, and how channel and regional variables compound to affect profitability. The full PW Consulting report delivers precisely that kind of actionable resolution.
Worldwide Lapis Lazuli Pendant Market
Readers seeking the complete segmentation breakdowns, competitive intensity scores, channel value-share details, and source-level material context should access the full publication to obtain the depth required for strategic action. What this introduction demonstrates is the analytical discipline and multi-layered perspective embedded in the study. What it intentionally withholds are the exact split figures and proprietary allocation details that give the report its decision-grade value. Those insights are available in the complete Worldwide Lapis Lazuli Pendant Market research, where strategy teams can convert market complexity into executable advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Lapis Lazuli Pendant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Next Wave: Strategic Intelligence for the Global Electric Ambulance Stretchers Market
The emergency medical services landscape is undergoing a profound transformation, driven by an aging global population, increasing emergency call volumes, and an uncompromising focus on paramedic safety and patient outcomes. In this high-stakes environment, the equipment used for patient transport is no longer mere hardware; it is a critical determinant of operational efficiency, staff retention, and clinical safety. PW Consulting's latest comprehensive study on the Worldwide Electric Ambulance Stretchers Market offers a decisive roadmap for stakeholders preparing for the 2026 fiscal year and beyond.
As agencies face tightening budgets and escalating compliance standards, understanding the trajectory of this specialized equipment segment is essential. This research brief outlines the strategic value embedded within our full market intelligence report, designed to empower procurement officers, investors, and C-suite executives with the foresight needed to navigate a complex and evolving competitive arena.
Market Trajectory: The Growth Imperative
The macroeconomic indicators for electric ambulance stretchers signal a robust and sustained expansion phase. Our analysis tracks historical performance from 2020 through the base year of 2025, projecting a clear upward trajectory that extends through the forecast period ending in 2032. The market has demonstrated resilience and consistent value appreciation, moving from a valuation of approximately 385.12 million USD in 2020 to an estimated 560.0 million USD in 2025.
Worldwide Electric Ambulance Stretchers Market
Looking toward the immediate future, the momentum가속 (accelerates) as we enter the 2026-2032 forecast window. The market is poised to reach significant new highs, driven by the replacement of legacy manual equipment with powered solutions that reduce physical strain on emergency responders. The compound annual growth rate (CAGR) stands at a compelling 8.31 percent, indicating that demand is not merely recovering but structurally expanding. For decision-makers, this growth rate suggests that investment in electric transport infrastructure is not a discretionary expense but a strategic necessity to maintain operational parity.
Emergency Stretcher Market
Competitive Landscape: Concentration and Innovation
The market structure is characterized by moderate to high concentration, with established players leveraging technological integration and fleet-scale contracts to secure market share. Our report details the positioning of key industry participants, including global giants like Stryker Corporation and Fenro-Washington, Inc., alongside specialized manufacturers such as Kartsana S.L. and several prominent Chinese medical equipment firms including Jiangyin Everise Medical Equipment Co., Ltd. and Jiangsu Rixin Medical Equipment Co., Ltd. (Red Leaf).
Understanding the rivalry requires more than recognizing brand names; it demands insight into how these companies are differentiating their offerings. Leading manufacturers are increasingly focusing on connected technologies, lithium-ion battery efficiency, and compliance with rigorous crash standards such as SAE J3027 and BS EN 1789. For instance, recent industry movements highlight the intensity of this competition. Major contracts are being awarded based on comprehensive RFP testing and facility visits, as seen in significant fleet agreements involving hundreds of powered units. Furthermore, the inclusion of specific electric powered ambulance gurneys in federal market surveys, such as the DHS SAVER program, underscores the importance of meeting standardized performance metrics across multiple jurisdictions.
The barrier to entry remains significant due to the technical requirements of load capacities ranging from 300 to 700+ lbs, battery reliability, and the need for manual backup systems in critical failure scenarios. However, the presence of multiple manufacturers across different regions indicates a healthy supply chain capable of meeting varied regional procurement needs, from North American GSA Schedule contracts to European compliance frameworks.
Regulatory and Operational Dynamics
Operational compliance is a pivotal factor shaping procurement strategies in the electric ambulance stretcher sector. Regulatory frameworks vary by region but converge on safety and electrical reliability. Powered wheeled stretchers occupy a specific niche within medical device regulations; notably, they are often exempt from 510(k) premarket notification requirements under FDA regulations for Class II devices in the United States. This regulatory distinction impacts time-to-market strategies for manufacturers and influences the vetting process for procurement agencies.
Beyond regulatory exemptions, adherence to physical and electrical safety standards is non-negotiable. Equipment must meet standards including IEC 60601-1 for medical electrical equipment, alongside flammability and durability requirements. For agency directors, navigating these specifications is critical to risk management. Procurement under GSA Schedule contracts in the U.S. adds another layer of complexity, requiring vendors to maintain specific contractual standings. Our report dissects these regulatory layers, providing clarity on how compliance influences total cost of ownership and supply chain reliability.
Segmentation: Strategic Focus Areas
While the overall market growth is impressive, the real strategic value lies in understanding where demand is originating and what technological configurations are gaining traction. The market is segmented by product type and end-user application, each offering distinct opportunities for stakeholders.
- Product Technology: The landscape is divided between hydraulic-electric hybrids and fully electric systems. Hydraulic-electric stretchers continue to hold significant market presence, leveraging established reliability and high load capacities. However, fully electric stretchers are gaining ground as battery technology improves, offering reduced operator injury and enhanced maneuverability. The choice between these systems often depends on the specific operational environment, ranging from urban paramedic services to military and defense applications where durability and specific load requirements are paramount.
- End-User Verticals: Demand is distributed across emergency medical service centers, hospitals and clinics, and military and defense sectors. Emergency Medical Service Centers remain a primary driver, given the direct impact of powered stretchers on paramedic health and efficiency during scene responses. Hospitals and clinics utilize these units for internal transport and inter-facility transfers, where ergonomic considerations are increasingly prioritized to reduce staff injury claims. The military and defense segment represents a specialized niche requiring ruggedized solutions that meet unique logistical and safety standards.
- Regional Variations: Market value is distributed across key global regions, with North America historically representing a substantial portion of revenue generation, followed by Europe and the Asia Pacific region. Latin America and the Middle East and Africa present emerging opportunities driven by infrastructure development and modernization of emergency response fleets. Understanding the nuanced demand drivers in each region—such as reimbursement structures, public vs. private procurement models, and local manufacturing capabilities—is essential for market entry or expansion strategies.
Report Scope: Actionable Intelligence for 2026
PW Consulting's Worldwide Electric Ambulance Stretchers Market research is designed to be more than a static snapshot; it is a dynamic tool for strategic planning. The full report provides a granular breakdown of the data required to make informed decisions in 2026.
Key components of the full study include:
- Historical and Forecast Data: Detailed revenue analysis from 2020 to 2032, allowing users to model growth scenarios and budget accordingly.
- Competitive Profiling: In-depth company profiles covering product specifications, recent developments, and strategic moves, enabling benchmarking against key rivals.
- Segment Analysis: A comprehensive look at product types, end-user applications, and regional distributions without the constraints of summarized data, offering the granularity needed for specific market entry or product development plans.
- Supply Chain and Sales Channels: Analysis of distribution networks and procurement pathways, including insights into government contracting vehicles like GSA schedules.
- Regulatory Landscape: A thorough examination of safety standards and compliance requirements affecting product design and procurement.
By accessing the full report, stakeholders can unlock the specific percentage splits and exact monetary values for each segment and region. This level of detail is crucial for validating investment theses, optimizing inventory levels, and tailoring marketing strategies to the highest-value segments.
Conclusion: The Cost of Inaction
In the electric ambulance stretchers market, the cost of inaction is rising. As paramedic health concerns grow and operational efficiency becomes a key metric for funding, agencies that rely on outdated transport equipment risk higher injury rates, slower response times, and increased liability. For manufacturers and investors, the 8.31 percent CAGR signals a market ripe with opportunity, but success requires precise navigation of the competitive and regulatory environment.
The data presented in this overview provides a foundation, but the complete strategic picture requires deeper analysis. The specific revenue contributions of each region, the precise market share of competing product types, and the detailed sales channel dynamics are reserved for the comprehensive report. We invite industry leaders to leverage this intelligence to secure their position in the evolving emergency medical equipment landscape. To access the full dataset, competitive matrices, and forward-looking forecasts necessary for your 2026 planning, please refer to the complete PW Consulting Worldwide Electric Ambulance Stretchers Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Electric Ambulance Stretchers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Aircraft Windows Market to Reach $1,162.16M by 2032, 4.25% CAGR
By pmarketresearch, 2026-09-16
Strategic Transparency: Navigating the Worldwide Aircraft Windows Market Outlook 2026-2032
The global aerospace industry is currently navigating a complex landscape defined by post-pandemic recovery, supply chain recalibration, and an aggressive push toward fuel efficiency. Within this ecosystem, the aircraft windows market serves as a critical barometer for broader manufacturing health, regulatory compliance, and technological innovation. As we enter 2026, stakeholders across the value chain—from original equipment manufacturers (OEMs) to maintenance, repair, and overhaul (MRO) providers—require precise intelligence to capitalize on emerging opportunities. PW Consulting is proud to introduce our comprehensive Worldwide Aircraft Windows Market research, a definitive guide designed to inform high-stakes corporate strategy over the next decade.
This report is not merely a collection of statistics; it is a strategic roadmap. It synthesizes historical performance from 2020 through 2025 with a robust forecast extending to 2032. By analyzing the trajectory from a market valuation of approximately 702.5 million USD in 2020 to a projected 1.16 billion USD by 2032, we uncover the underlying forces driving growth. The compound annual growth rate (CAGR) of 4.25 percent signals a steady, resilient expansion, yet the nuances behind this aggregate figure hold the key to competitive advantage. Our analysis delves into the segmentation splits, material innovations, and regional dynamics that general industry reports often overlook, providing the granularity necessary for actionable decision-making.
Market Trajectory and Macro Drivers
Understanding the historical context is essential for validating future projections. The market demonstrated consistent resilience between 2020 and 2025, recovering from initial disruptions to reach an estimated 868.42 million USD in the base year. This recovery sets the stage for the forecast period beginning in 2026, where valuations are expected to climb from 908.11 million USD to over 1.1 billion USD by 2032. Such growth is not organic fluke; it is anchored in tangible macroeconomic and industry-specific drivers.
Several macro trends are converging to sustain this demand. Strong global passenger demand continues to fuel air travel recovery, necessitating both new aircraft production and significant retrofit programs for aging fleets. Industry forecasts indicate over 2,000 annual narrowbody deliveries projected from 2027 onwards. Each new airframe requires a full suite of transparencies, while retired fleets undergoing modernization require updated window assemblies to meet contemporary safety and comfort standards. Furthermore, the Airbus 2025 Global Market Forecast projects a passenger traffic CAGR of 3.6 percent to 2044. This long-term traffic growth ensures that demand for new passenger aircraft and their associated transparencies will remain robust, creating a sustained pipeline for window manufacturers and suppliers.
Aircraft Flooring Market
Additionally, regulatory frameworks are tightening. Pressure from authorities such as the FAA and EASA is driving more frequent windshield replacement cycles to ensure safety and compliance in commercial aircraft. These regulatory mandates act as a floor for aftermarket demand, ensuring that even during fluctuations in new aircraft orders, the MRO segment remains active. Our report quantifies how these regulatory cycles interact with material lifespans to create predictable revenue streams for service providers.
Worldwide Aircraft Windows Market
Material Innovations and Segment Dynamics
The aircraft windows market is segmented by product type, material, and platform, each presenting unique value propositions and challenges. Our research dissects these segments to reveal where margin potential lies. By product type, the market is divided between cabin windows and cockpit windows. While cabin windows represent a significant portion of the volume due to the number of units per aircraft, cockpit windows demand higher precision and optical fidelity, often commanding different pricing structures and supply chain requirements.
Material selection is perhaps the most critical technical decision facing engineers and procurement teams. The industry is currently weighing the trade-offs between acrylic, glass, and polycarbonate. Traditional stretched acrylic remains common for cabin windows due to its proven performance and cost-effectiveness. However, polycarbonate is gaining traction, offering up to 40 percent less weight than glass alternatives. In an industry obsessed with fuel efficiency and carbon reduction, this weight savings is a compelling value driver. Conversely, glass laminates held a significant share in commercial aircraft windows and windshields in 2025 due to superior optical fidelity and scratch resistance.
Our analysis highlights that while glass maintains dominance in specific high-performance applications, the polycarbonate segment shows a stronger growth trajectory. This shift is not uniform across all platforms. Commercial aviation continues to be the largest platform segment, driven by the sheer volume of passenger aircraft. However, military aviation and business and general aviation segments offer specialized opportunities. Military transparency systems require ruggedization and specific coating technologies for survivability, while business aviation focuses on luxury, noise reduction, and bespoke customization. Understanding the interplay between material costs, weight savings, and platform requirements is essential for suppliers positioning themselves in 2026 and beyond.
Competitive Landscape and Strategic Positioning
The market structure is moderately concentrated, with the top three companies holding a significant share of the revenue pool. This concentration suggests that while barriers to entry exist, there is still room for specialized players in niche segments such as general aviation or aftermarket repairs. Our report provides detailed profiles of key companies shaping the competitive environment, analyzing their strategic moves, product portfolios, and geographic footprints.
Major players such as PPG Aerospace and GKN Aerospace dominate large portions of the original-equipment and aftermarket transparency markets. PPG Aerospace is recognized for its advanced coatings, including SOLARON BLUE PROTECTION UV+ blocking technology, which enhances passenger comfort and reduces cabin heat load. GKN Aerospace stands as a world-leading provider of military transparency systems and holds a strong second position in the commercial aircraft transparency market, with over 2 million CrystalVue II coated windows in service. Their focus on aerospace-grade acrylic and advanced coatings underscores the industry trend toward multifunctional window assemblies.
Saint-Gobain Aerospace continues to supply aircraft windows and windshields trusted by airlines worldwide. A notable recent development includes their partnership with Lilium to supply and support windows and windshields for the Lilium Jet, signaling a strategic pivot toward emerging electric vertical takeoff and landing (eVTOL) and advanced air mobility platforms. This move highlights how traditional aerospace suppliers are diversifying into next-generation aviation sectors.
In the aftermarket and general aviation space, specialized manufacturers play a crucial role. Lee Aerospace specializes in FAA-approved aircraft windows and windshields for business and general aviation aircraft, including brands like Bombardier, Cessna, and Gulfstream. They offer CoolView upgrades and robust aftermarket support, catering to owners seeking performance enhancements. Similarly, L.P. Aero Plastics Inc. stands as a leading FAA-PMA manufacturer of aircraft windshields and windows for the general aviation market with over 60 years of history. Perkins Aircraft Windows manufactures, repairs, and installs business aircraft windshields and cabin windows for a wide range of models, including Citation, Challenger, Embraer, and Falcon.
Other key entities include The NORDAM Group, which provides repair, overhaul, and manufacturing services as part of its global aerospace MRO solutions, and Gentex Corporation, focusing on advanced optical and protective systems. Smaller but significant players like Cee Bailey's Aircraft Plastics and Llamas Plastics, Inc. produce light aircraft windows and transparencies meeting high optical requirements. The presence of these specialized firms indicates a healthy ecosystem where large monopolies coexist with agile specialists capable of serving niche requirements.
Strategic Implications for 2026 Decision Makers
For executives and strategists, the data presented in this report translates into several critical imperatives. First, supply chain resilience is paramount. The concentration of key players in specific regions suggests that geopolitical shifts or localized disruptions could impact availability. Diversifying supplier bases or investing in regional manufacturing capabilities may be necessary to mitigate risk. Second, material innovation offers a pathway to differentiation. Companies that can effectively integrate lightweight polycarbonate solutions without compromising optical quality or safety certifications will capture premium market segments.
Third, the aftermarket presents a stable revenue anchor. With regulatory pressure driving replacement cycles and fleets aging, the MRO segment for windows and windshields is poised for growth independent of new aircraft delivery rates. Service providers who invest in certification and capacity for these replacement cycles will secure long-term contracts. Finally, the emergence of new platform types, such as the Lilium Jet partnership exemplifies, suggests that agility in adapting window technologies to novel airframe designs will be a key differentiator.
Our report goes beyond surface-level observations to provide the operational details needed to execute these strategies. It includes comprehensive scope definitions, research methodologies, and an in-depth analysis of market dynamics that influence pricing, adoption rates, and regional performance. We examine the regulatory landscape, raw material cost structures, and the specific technological advancements that are reshaping the value chain. By integrating quantitative data with qualitative industry context, we provide a holistic view that supports investment appraisal, product development roadmaps, and market entry strategies.
Conclusion
The Worldwide Aircraft Windows Market is at an inflection point. The convergence of rising passenger traffic, regulatory mandates, and material science advancements creates a fertile environment for growth. However, navigating this landscape requires more than general market awareness; it demands precise, data-backed insight. PW Consulting's latest research empowers organizations to look past the aggregate numbers and understand the specific drivers that will define success in 2026 and beyond.
To access the full depth of this analysis, including detailed segmentation data, competitive benchmarking, and region-specific forecasts, we invite you to explore the complete report. The strategic advantages hidden within the data are available to those ready to invest in comprehensive intelligence. Equip your organization with the knowledge needed to steer through the complexities of the aerospace supply chain and capitalize on the transparency revolution.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Windows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com